
❌

Reading view

Be Prepared for Elizabeth Warren's Reign of Economic Error
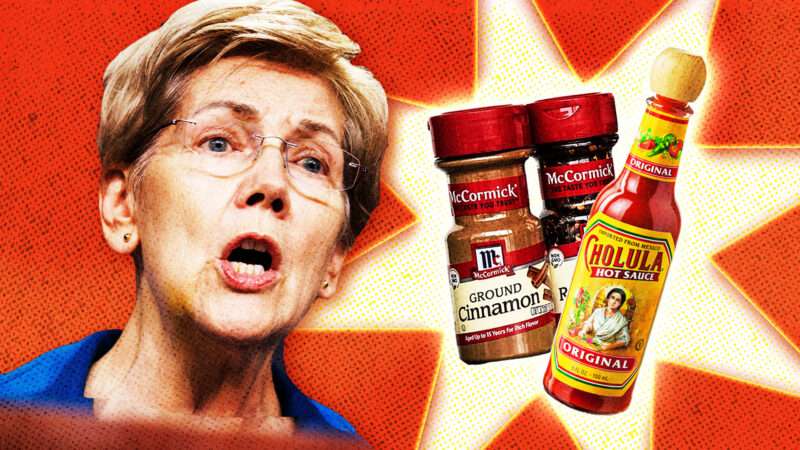
Massachusetts Senator Elizabeth Warren and bottles of condiments | Samuel Corum/Sipa USA/Newscom/Viennetta/Dreamstime/Cinnamonspice241/Wiki Commons/Fatima Ruiz.

With little more than two weeks to go until the midterm elections, it seems increasingly possible that the Democrats, already a big favorite to win control of the House of Representatives, will also take charge of the planet's most elite nursing home, the United States Senate, where the median age is 64 years old. RealClearPolitics' poll aggregator has moved control of "the world's greatest deliberative body" (as its members are grandiosely wont to call it) to "toss up," status and prediction markets are now breaking big toward a blue wave. As of this writing, Kalshi has its Senate odds at 63 percent for the Dems vs. 37 percent for the GOP; Polymarket is at 62 percent vs. 39 percent.

As gratifying as it might be to see unprincipled Trump enablers reduced to minority status after signing off on economy-wrecking tariffs, inhumane immigration detentions, and wars of choice, there's at least one good reason to dread a Democratic majority too: Sen. Elizabeth Warren, the Massachusetts progressive who is spending the run-up to the midterms freaking out over possible consolidation in the condiments business and accusing private equity firms of gutting such shopping-mall favorites as Claire's and Toys R Us. There's every reason to believe that a Senate run by Warren and other economic interventionists will waste time, money, and resources trying to prevent a world in which, per the X wag Iowahawkblog, "a panopticon conglomerate owns two brands of hot sauce."

On October 13, Warren posted this dire warning to X:

Hellmann's mayo
McCormick spices
Cholula hot sauce
Frank's RedHot

What do these products have in common? One company could soon control them all.

I have concerns that McCormick and Unilever's $45 billion merger could increase YOUR grocery prices.

— Elizabeth Warren (@SenWarren) October 13, 2026

It's hard to think of a more competitive and varied market than the one for hot sauces, which is expected to more than double over the next decade. The barriers to entry are generally low, as are the key ingredients, and new entrants can easily market and sell online, avoiding the costs of buying shelf space in conventional supermarkets. Yet Warren is urging regulators at the Department of Justice and the Federal Trade Commission to halt mergers of both product makers like McCormick and Unilever and grocery stores like Kroger and Giant Eagle.

The latter complaint is particularly picayune. Kroger is one of the country's largest supermarket chains, operating around 2,800 stores under its own name as well as Harris Teeter, Ralph's, and others. Giant Eagle operates about 170 stores. This merger is no more the stuff of nightmares than a single company producing both Cholula and Frank's RedHot. If Warren gains more clout from being in the majority, expect her to butt in more and more on such mergers.

Making it harder for businesses to adapt is not a recipe for making goods and services more affordable. But Warren is keen to blame economic creative destruction not on "new forms of industrial organization that capitalist enterprise creates" (as Joseph Schumpeter would have it), but on pure greed. In a TikTok released earlier this month, she shows a poster board with corporate logos from once-thriving companies that she says have been "gutted" by "private equity" firms.

"Here's your local mall," she piously intones. "Now, private equity wants you to believe that Red Lobster went bankrupt because of their endless shrimp….They want you to believe that Claire's went bankrupt because teens stopped shopping at the mall." In Warren's telling, private equity firms magically take over thriving businesses and then strip them bare. The typical pattern is that private equity enters the picture after a business is failing.

Virtually all accounts of the decline of, for example, Red Lobster, note that the chain had been spiraling for several reasons before the private equity firm Golden Gate Capital got involved in 2014. As this CNN article notes, the chain, which started in 1968, had seen drops in sales as customer desires changed. Management compounded the difficulties with a series of bad decisions, including continuing various all-you-can-eat menu specials, before coming out of Chapter 11 bankruptcy last year.

Similarly, it's true that some teens still go to malls and get their ears pierced at Claire's. But anyone who has spent time in retail America over the past few decades knows that malls are no longer the destination that they once were. As CapitalOne Shopping Research documents, "in 1986, there were 25,000 malls, large and small, nationwide." By 2023, that number had shrunk to just 1,200. While some malls are coming back, most are not, and for reasons that have nothing to do with private equity. Online retails plays a role (though a smaller one than usually imagined, with e-commerce accounting for less than 20 percent of all retail sales). But mostly, it's that people today tend to want a different sort of retail environment. Anchor stores—think Macy's and J.C. Penney—are shadows of themselves, and younger people have less unstructured time in which to prowl food courts and arcades.

For politicians like Elizabeth Warren, though, there can be no financial gains or losses that aren't the result of shadowy, conspiratorial forces. If her party takes control of the Senate, her words will carry more weight. But it will be American consumers that ultimately shoulder the burden of an even-more-regulated economy. The market for hot sauces will almost certainly stay spicy, but many other parts will surely suffer.

The post Be Prepared for Elizabeth Warren's Reign of Economic Error appeared first on Reason Magazine.
  •  

Germany Protects Deutsche Börse as EU Ministers Agree Reduced Financial Supervision Reform

EU finance ministers have approved a compromise that would expand the European Securities and Markets Authority’s powers while exempting some major trading venues from centralised oversight. The agreement reflects continuing resistance to transferring financial supervision from national authorities to Brussels.

European Union finance ministers have reached an agreement to expand centralised supervision of financial markets, but Germany has secured provisions allowing important parts of Deutsche Börse to remain under national oversight, substantially narrowing the European Commission’s original reform proposals.

The compromise, agreed at a meeting in Luxembourg on 9 October, would transfer responsibility for supervising selected trading venues, clearing houses and securities settlement institutions to the European Securities and Markets Authority (ESMA).

However, the agreement introduces exemptions and thresholds that reduce the number of institutions automatically subject to direct European supervision.

The result is a significant political compromise between governments seeking deeper financial integration and those reluctant to surrender oversight of nationally important market operators.

Berlin secures its exemption

The most contentious element of the negotiations concerned Deutsche Börse, the German financial-market group that operates the Frankfurt stock exchange and provides trading, clearing and other financial infrastructure services.

Germany opposed arrangements that would place all major market operators under direct ESMA supervision, arguing that institutions with predominantly domestic activities should continue to be regulated nationally.

The agreed compromise refines the criteria for determining which trading venues qualify for centralised oversight.

These conditions allow certain Deutsche Börse operations to remain outside the new supervisory regime.

The exemption had already become a point of contention during negotiations among European governments.

As EU Today reported in June, Berlin had sought to protect Deutsche Börse from mandatory European supervision despite Germany’s broader support for integrating EU capital markets.

The October agreement formalises a narrower approach within the Council’s negotiating position, although the legislation remains subject to approval by the European Parliament.

Europe’s fragmented financial markets

The European Commission has repeatedly argued that fragmented national supervision weakens the EU’s ability to compete with financial markets in the United States.

Although the Union operates a single market, many financial institutions continue to face differing regulatory interpretations, procedures and supervisory relationships across member states.

These differences can increase operating costs and discourage financial businesses from expanding across borders.

The Market Integration and Supervision Package is intended to simplify those arrangements and strengthen common oversight of financial infrastructure with significant cross-border activity.

Under the Council’s position, ESMA would assume direct supervision of selected trading platforms and institutions involved in clearing and securities settlement.

Such institutions perform essential functions in financial markets, including managing transactions, transferring securities and controlling risks between counterparties.

Differences in supervisory arrangements can complicate the operation of financial services that increasingly function across national borders.

The Commission argues that greater consistency would allow European capital to move more efficiently between member states and provide businesses with improved access to investment.

Compromise reduces original ambitions

The Commission’s original approach envisaged broader centralisation of supervisory responsibilities.

The Council agreement of 9 October introduces more restrictive criteria governing the institutions that would fall under ESMA’s direct authority.

In addition to the treatment of trading venues, ministers agreed that direct supervision of crypto-asset service providers should initially concentrate on businesses with the most significant cross-border operations.

The Council also supported changes to ESMA’s governance arrangements, including the creation of a full-time executive board.

The proposed board would strengthen the authority’s ability to make supervisory decisions independently of individual national regulators, while preserving mechanisms for cooperation with those authorities.

The compromise also introduces arrangements allowing national supervisors collectively to challenge certain decisions.

These provisions reflect concerns about concentrating regulatory powers within an institution that must oversee financial businesses operating under different national legal systems.

Why capital markets matter for European investment

The supervision reforms form part of the EU’s broader Savings and Investments Union initiative.

European policymakers want to increase the availability of private capital for companies investing in technology, defence, infrastructure and industrial development.

The Union has substantial household savings, but much of that money remains in bank deposits or is invested outside the European economy.

Companies seeking capital for expansion may consequently face higher financing costs or more limited investment opportunities than comparable businesses operating in larger and more integrated markets.

The Commission’s Savings and Investments Union programme seeks to improve access to finance and make cross-border investment more attractive.

Financial-market supervision represents only one element of that programme.

Differences in taxation, insolvency law, national investment products and corporate governance requirements also influence where investors allocate their money.

Nevertheless, regulators regard consistent supervision as an important condition for reducing fragmentation.

Parliament faces a political decision

The agreement reached by finance ministers does not conclude the legislative process.

The European Parliament must adopt its position before negotiations can determine the final provisions.

Parliamentary discussions could revisit the exemptions secured by Germany and the criteria determining which institutions fall under direct ESMA supervision.

The debate will expose differences over whether European financial integration should proceed through incremental reforms or a more substantial transfer of regulatory authority.

Governments supporting national exemptions argue that supervision should reflect the actual geographic scope of a company’s activities.

Supporters of broader European oversight contend that major trading businesses can influence financial markets beyond their home jurisdictions even when individual operations appear predominantly domestic.

The Deutsche Börse exemption has become a prominent example of the conflict between those positions.

Europe’s largest economies broadly support the objective of deeper capital markets, but remain divided over the institutional powers needed to achieve it.

The final legislation will determine whether the expanded responsibilities granted to ESMA are sufficient to reduce fragmentation or leave important parts of Europe’s financial infrastructure operating under substantially different national supervisory systems.

  •  
❌