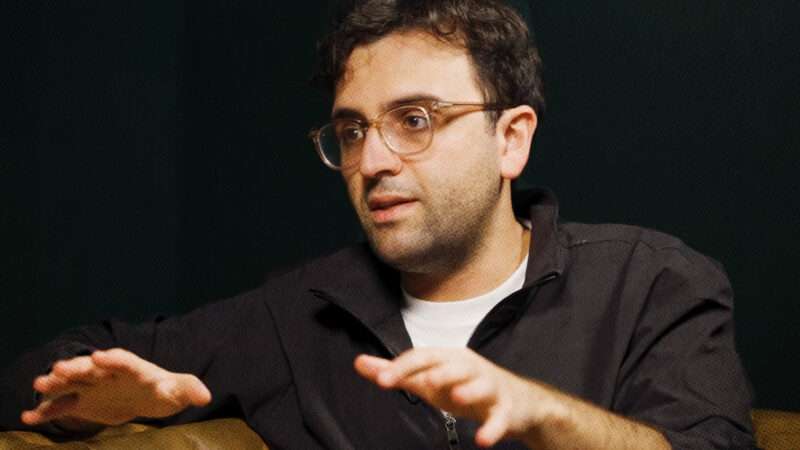
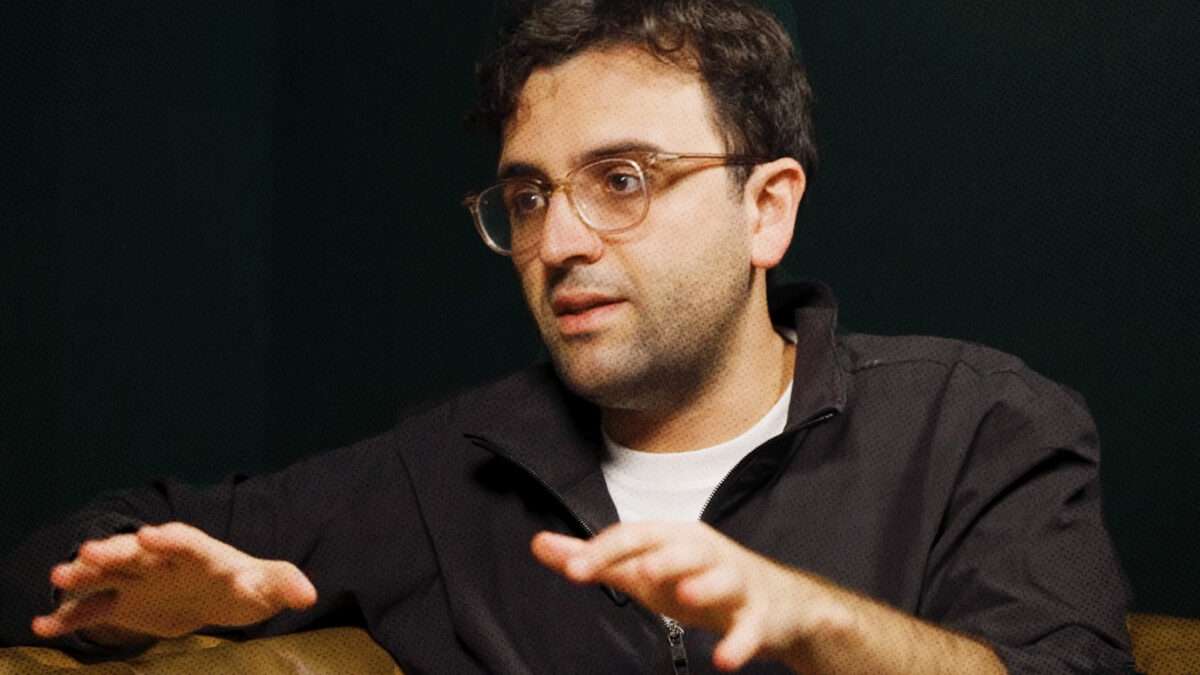
"I think capitalism is a good thing, but I think what we need to contend with and be aware of is that a lot of people are not part of it," Tarek Mansour, co-founder and CEO of prediction market platform Kalshi, recently toldReason's Nick Gillespie. "They don't feel like they're part of it. And that's a reality."
Mansour has set out to change that by making it easier for consumers to experience and participate in financial markets. Kalshi's premise is simple: Mansour says the platform matches traders with differing opinions on the outcome of future events, aggregating the "bits and pieces of information" siloed across the country, so long as that information isn't privileged or obtained illegally.
He's up against a rising number of federal and state lawmakers—not to mention the NFL, traditional sportsbooks, casinos, and other regulated gambling operations—who view Kalshi as yet another gambling app. "As of early 2026, more than 20 lawsuits and cease-and-desist actions are pending across the country, filed by state attorneys general, gaming regulators, tribal governments and private plaintiffs," according to the National Conference of State Legislatures. This includes Utah, whose attorney general, Derek Brown, escalated an ongoing legal dispute with Kalshi on Tuesday by filing a complaint against the prediction market in state district court. In his complaint, Brown called Kalshi an "unconscionable and illegal gambling operation." He accused the company of engaging in a "brazen pattern of unlawful conduct."
At the federal level, Bloomberg Lawreported last Friday that Sen. Ted Cruz (R–Texas) is preparing to introduce a bill after the midterm elections that would give state and tribal governments authority to regulate sports-related event contracts offered by prediction markets.
Cruz's state-by-state regulatory regime is exactly the kind of scheme Mansour wants lawmakers to avoid. Mansour recently toldReason that, ideally, there'd be a "federal uniform set of rules that apply across all 50 states." Those rules would then "promote and foster" a "multilateral, peer-to-peer idea," where, for example, someone in California, Oregon, or Washington could trade on an event's outcome based on information supplied by someone in Texas.
Mansour, who calls insider trading an "unfair dynamic that over time dries up liquidity," also argues that prediction markets are uniquely positioned to self-regulate because trades on Kalshi are "fully transparent," making it "easy to flag" suspicious trading patterns. The platform's users play a key role in that work. Mansour says that in February, when convicted fraudster and former Rep. George Santos (R–N.Y.) tried to engage in insider trading, Kalshi received "a hundred whistleblower complaints within a few minutes."
The company's public commitment to rooting out insider trading on its platform may be laudable. Still, it has done little to dispel the prevailing sentiment among state and federal regulators that Kalshi—and prediction market platforms writ large—is indistinguishable from traditional gambling markets.
Indeed, the legal cases against Kalshi are centered on state regulators' belief that the platforms' sports event contracts are the same as the bets offered by legal gambling operations like casinos and sportsbooks. Kalshi has argued that the U.S. Commodity Futures Trading Commission has exclusive jurisdiction to regulate the kinds of contracts it can offer under federal law, preempting states from exercising any gambling authority over prediction markets.
In March, Arizona became the first state to file criminal charges against Kalshi. Arizona Attorney General Kris Mayes accused the company of "running an illegal gambling operation and taking bets on Arizona elections, both of which violate Arizona law." Not everyone in the state shares Mayes' view. One Arizona resident, Zach, a 35-year-old man who makes a living trading sports-related event contracts on prediction markets, tells Reason he'd "move to another state" if Arizona succeeds in driving out prediction markets.
"There's nothing that is excluding other people from the profits that I'm making right now," he says. "I'm under no obligation to bet on Monday Night Football….I'm able to look at all the markets and decide which ones I want; I'm setting a limit order and just saying, 'OK, if I get my price, then hooray.' If I don't, then that's not something that I add to my portfolio."
Of course, not everyone acts as responsibly. Mansour knows that in any competition, including trading, "some people are going to win," while "some people lose." He believes in "individual freedom" and in the idea that "people should be able to choose" which financial markets they engage in, with "some regulations on irresponsible use" so that companies can't target people who exhibit addictive or destructive betting patterns.
The degree to which Kalshi and other prediction market platforms should be regulated will likely be a high priority for federal lawmakers after the midterm elections and in the next Congress. Mansour appears optimistic that there's enough bipartisan support for what he calls "sensible guardrails." He says there's a "big group" on both sides of the aisle that's "actually pro" prediction market platforms. There's reason to be skeptical of Mansour's claim, given that several members of Congress—such as Sen. Elizabeth Warren (D–Mass.), the ranking Democrat on the Senate Banking Committee—have said prediction markets need to be reined in.
In Mayes' case, her antipathy toward prediction markets might cost her at least one vote in Arizona's attorney general race. Zach says that with Mayes waging a legal battle against Kalshi, he'd have to take that into account "hypothetically, if someone knocked on my door tonight and they want me to vote for Kris Mayes to be reelected."
"If I'm not gonna vote on my own behalf, then who is, right?" he says. (Mayes might not be a fan of Kalshi, but with the platform's penchant for accurately predicting election winners, she can take solace in her current trading position, which shows an 84 percent chance she retains her position.)
Mansour says he's a "free market guy" who wants everyone to "have a shot in the competition." To succeed, he'll have to withstand a host of paternalistic government officials hell-bent on controlling financial decisions made by consenting adults.
How much savings you need to retire in 2026 depends on county and housing, from Brooklyn renters to mortgage-free Raleigh homeowners in SmartAsset's 55-county study
Of all the arguments for protectionism, the infant industry argument probably has the strongest theoretical appeal. By protecting a new industry from its more developed foreign competition, the story goes, tariffs give domestic producers the time to grow, learn, and become efficient enough to stand on their own. Domestic consumers feel the short-term pains of higher prices, but they enjoy the long-term gains of job growth and lower prices as the new industry blossoms.
It's no secret that tariffs have driven significant price increases over the last year and a half. A study from the New York Federal Reserve finds that tariffs "contributed 2.9 percentage points to goods price inflation" and that without tariffs those prices would have slightly declined. Tariff defenders, looking for a new reason to claim these higher prices are only temporary, have reimagined the infant industry argument. Now it's being used to support trade barriers in industries that are over a century old, but the promise is exactly the same: Domestic firms need the protection so they can compete, innovate, and cut costs until prices come back down even further than they were before the tariffs.
Michael Brendan Dougherty recently made such an argument in National Review, arguing that "tariffs can, over time, bring prices below where they started." When economist Don Boudreaux called the argument "bizarre," Dougherty replied that critics had failed to acknowledge the dynamic process by which markets respond to tariffs "by adapting and cutting costs." Although he is light on specific details, he posits that the changed incentives of a "paradigm shift" in tariff policy will spur domestic competition, leading to the theorized price reduction. Of course, firms would still respond to the dynamic processes of domestic competition without a tariff wall, but the point stands.
From there, the reworked infant industry argument becomes the standard version advanced more than two centuries ago by Alexander Hamilton and his disciple Friedrich List. When Hamilton made this claim in 1791, his argument may have seemed suitable for a new nation seeking to firm up its economy and security against established European powers.
Others at the time pointed out that special interest groups—a manifestation of the "violence of faction" so thoroughly dissected in theFederalist Papers—had already begun to coalesce around the fledgling iron industry in Pennsylvania, clamoring for protective tariffs. Two years earlier, James Madison had warned about a "premature policy of stimulating manufactures" driving tariffs too high. In the end, Hamilton recommended and Congress enacted a far more moderate tariff schedule than his theoretical musings portended. American iron manufacturers received a consolation prize of a higher tariff on their competitors than the rate for most general imports. Hamiltonians have been touting the infant industry argument ever since.
Nearly 250 years later, those same infants apparently have yet to advance into adulthood. Steel, the direct successor to the founding-era iron manufacturers, remains a singular focus of President Donald Trump's protectionist tariff policies, just as it was under former President Joe Biden. And former President George W. Bush before him. Indeed, steel has been a recurring beneficiary of protectionism for most of America's existence.
This extended period of protectionist infancy suggests that the argument needs a new name. We propose the "Peter Pan industry argument" for companies that never grow up because tariffs make sure they never have to.
The question tariff advocates rarely ask is: Why do some American producers have higher costs than foreign rivals even in the face of lower-cost foreign competition? The answer comes down to specific rules and choices within particular firms and industries. Tariffs, and protectionism in general, address none of these. No industry illustrates this like steel, but it is far from the only one.
In 1947, United Steelworkers won a contract provision known as Section 2-B. Among other things, this barred mill managers from changing established work practices unless new technology required it. Steel companies tried to get rid of this in 1959, finding it difficult (given union incentives) to establish that technology required change. In response, 500,000 steelworkers went on strike for 116 days. This strike sent buyers abroad, causing 1959 to be the first year the U.S. imported more steel than it exported. One of the then-new technologies that was delayed was basic oxygen furnaces, which could produce steel far faster and cheaper than the open-hearth furnaces that were so common. In 1965, only about 17 percent of steel made in the U.S. was made using the basic oxygen furnace. Japan produced 55 percent of its steel with this faster, more efficient method.
Change finally came from a steel customer. Vulcraft, a maker of steel joists, grew tired of paying Big Steel's prices and waiting for Big Steel's deliveries. In 1969, free from steel unions and preconceived notions, the company looked for new steel-producing technologies and found the answer in the electric arc furnaces that had been adopted in much of the world throughout the 1950s and '60s. Vulcraft's parent company later renamed itself Nucor, and minimills like the ones it pioneered now make most of America's steel.
So the modern steel industry was built by a frustrated steel buyer who found a way around protected companies. In other words, the U.S. steel industry has lagged behind the technologies found around the world.
We could go on, but the broad point here is that the "relatively higher domestic production costs that made the tariff 'necessary' in the first place," as one critic put it, are often the result of preventing competition in the first place. It's odd to suggest that further preventing competition through tariffs will somehow alleviate the ills of already-prevented competition.
Tariff advocates fail to acknowledge that the ability to import steel also comes with the benefit of access to cheaper steel for steel-using industries, such as manufacturing. A 50 percent tariff on steel further closes the release valve that imported steel offers. Buyers of steel are then left to purchase more of the more expensive domestic steel. Because new steel mills take years to bring online, this causes delays and longer delivery times for manufacturers.
We don't have to wonder what happens when a country lowers its tariffs on materials used by manufacturers. India did this in the '90s, and researchers found that newly available inputs accounted for 31 percent of the new products that Indian manufacturers introduced. And what happens when the U.S. imposes tariffs on steel? Downstream U.S. firms become less competitive. This is why American businesses clamor for exemptions to tariffs, especially for tariffs on materials like steel.
Perhaps all this could be forgiven if tariffs advanced national security concerns, as tariff advocates assert. They point out that an adversarial nation could cut off supplies of critical materials during wartime and cripple America's ability to defend itself. Unfortunately, tariffs fail there too.
First, this conflates production with access. While domestic production does ensure domestic access, access can be secured without production. In the case of steel, the Commerce Department reports that in 2025, the U.S. imported steel from 79 countries, with Canada being our top foreign supplier. The top 10 sources of steel are responsible for 77.8 percent of America's steel imports. None of those countries were considered adversaries—at least not until the tariff crusades pushed these friends away. What's more, according to the American Iron and Steel Institute, only 23 percent of finished steel in the U.S. was imported in 2024. Far from being exposed to foreign states' whims, American access to steel is incredibly resilient.
Second, this view ignores the positive effects of trade and globalization on national security. The Center for Strategic & International Studies finds that increased trade between countries reduces the likelihood that they'll go to war against one another. Globalization helps ensure that domestic access continues unabated should war break out, thanks to the diversity of trading partners.
When Hamilton made the infant industry argument, he at least assured us that the industry would at some point advance to adulthood and stand on its own. Steel, like so many other Peter Pan industries, has proven Madison right. These industries have refused to grow up, and it's time to stop pretending that tariffs will fix that.
The 2027 tax brackets are projected to rise 3.2% for inflation, letting single filers and married couples earn more before hitting each higher federal rate
Drops for stocks in the artificial-intelligence industry are dragging markets down worldwide on Thursday, while oil prices hit their highest levels since May amid the Iran war.
 Login