❌

Reading view

Volkswagen’s €5.9 Billion Loss Exposes Deepening Crisis in German Car Industry

Volkswagen has reported a quarterly operating loss of €5.9 billion, intensifying pressure for factory restructuring and workforce reductions as Europe’s largest carmaker struggles with Chinese competition, American trade tariffs and the financial costs of its transition towards electric vehicles.

Volkswagen Group has announced a €5.86 billion operating loss for the third quarter of 2026, marking another deterioration in the financial performance of a company long regarded as one of the foundations of German industrial strength.

The result, published on 29 October, compares with an operating loss of €1.3 billion in the corresponding period last year.

Quarterly revenue declined by 6.3 per cent to €75.3 billion, while vehicle deliveries fell by 14.3 per cent to approximately 1.89 million.

The figures highlight the scale of the challenges facing the automotive group, which includes Volkswagen, Audi, Porsche, Škoda and several other major European brands.

They also increase pressure on management to accelerate a restructuring programme involving substantial reductions in costs, employment and production capacity.

Porsche Writedown Weighs on Results

A substantial part of Volkswagen’s reported loss was attributable to exceptional charges, including a multibillion-euro reduction in the assessed value of its Porsche interests.

According to Volkswagen’s financial results, the group’s operating result for the first nine months of 2026 was just €71 million, compared with €5.4 billion during the equivalent period of 2025.

Excluding special items, the company recorded an operating profit of €8.8 billion for the nine-month period.

The distinction is important.

The latest results do not indicate that every part of Volkswagen’s underlying business is generating operating losses. However, they expose the financial consequences of weakened profitability, changes in business strategy and previous investment decisions.

The group’s operating margin before special items stood at 3.8 per cent.

Finance chief Arno Antlitz said this was insufficient to sustain the investment needed for future competitiveness.

Volkswagen’s difficulties have also coincided with pressure on Porsche, whose premium positioning has not insulated it from changing demand and competition in international markets.

China Becomes an Increasingly Difficult Market

China has been central to Volkswagen’s international business for decades, providing a major source of sales and earnings.

That position is increasingly challenged by domestic manufacturers offering competitive electric vehicles, advanced digital features and lower prices.

Chinese companies have expanded rapidly in their home market, often developing new models more quickly than established European manufacturers.

Volkswagen is therefore confronting a problem that extends beyond a cyclical slowdown in demand.

Its historical advantages in manufacturing scale, distribution and brand recognition no longer guarantee the same competitive position in a market undergoing technological transformation.

The company has acknowledged that the Chinese market is shrinking while competitive pressure in Europe is increasing.

American tariffs have created another complication, raising costs and constraining profitability in a market where the group already faces substantial competition.

Together, these developments have weakened the assumptions underpinning Volkswagen’s global manufacturing strategy.

Electric Vehicles Present a Financial Dilemma

Volkswagen has invested heavily in electrification, software development and new vehicle platforms.

Demand for its electric models in Europe remains significant.

The company reported that battery-electric vehicles account for 40 per cent of its European order book, while its Electric Urban Car Family has attracted approximately 150,000 orders.

However, increasing electric vehicle sales do not automatically produce higher profits.

Volkswagen acknowledges that its electric vehicles currently generate lower earnings than comparable combustion-engine models.

This creates a difficult financial transition.

The company must invest in technologies required to remain competitive while maintaining sufficient profitability to finance those investments.

At the same time, established European manufacturers face competition from Chinese producers with different cost structures and supply-chain arrangements.

The resulting pressure is not confined to Volkswagen. It affects suppliers, component manufacturers and other companies dependent on the European automotive industry.

Factory Closures and Employment Reductions

Volkswagen’s deteriorating results have strengthened management’s argument for reducing production costs.

Reuters reported that chief executive Oliver Blume’s wider restructuring proposals could involve as many as 100,000 job reductions across the group, with up to four German factories potentially facing closure.

These remain restructuring proposals rather than completed measures.

Volkswagen’s own Future Plan 2030 includes a cost-reduction programme worth approximately €31 billion, combining €20 billion in operational savings with €11 billion in lower overhead costs.

The company is also seeking an additional reduction of 12,000 positions at Volkswagen AG by 2030, with negotiations covering the proposed measures.

Management and the IG Metall union have agreed to begin talks on 24 November at the Emden plant, followed by another round in Zwickau on 15 December.

The negotiations are likely to prove consequential for industrial relations in Germany, where Volkswagen operates within a system of employee representation and collective bargaining that gives workers considerable influence over restructuring decisions.

A Wider Test for Europe’s Industrial Strategy

Volkswagen’s difficulties reflect several pressures facing European manufacturing.

High energy costs, international trade restrictions, technological competition and the expense of industrial transformation are affecting the profitability of established producers.

Europe’s automotive industry also supports extensive supplier networks, research facilities and skilled employment across several EU countries.

A sustained contraction in German vehicle production would therefore have implications beyond Germany itself, particularly for neighbouring economies integrated into automotive supply chains.

For EU policymakers, the challenge is to reconcile industrial competitiveness with decarbonisation objectives and the need to preserve manufacturing investment.

Volkswagen’s latest results do not determine the future of European car production. They do, however, demonstrate that the transition towards new technologies is taking place under considerably more difficult commercial conditions than many manufacturers anticipated.

The group’s restructuring negotiations will provide an early indication of how those costs are to be distributed between shareholders, employees and the industrial regions that depend on its factories.
  •  

Britain’s Post-Brexit Trade Dilemma Deepens as Brussels Advances ‘Made in Europe’ Rules

With a crucial EU–UK summit approaching, London is seeking assurances that British manufacturers will not be disadvantaged by Europe’s new industrial policies. The dispute exposes a wider problem: how closely Britain must align with Brussels to preserve access to European supply chains.

Britain and the European Union are attempting to resolve an increasingly consequential dispute over European industrial policy, as proposed rules favouring domestically manufactured goods threaten to complicate the economic relationship that London has spent much of the past year trying to rebuild.

Business Secretary Jonathan Reynolds said on 27 October that the two sides were making progress towards addressing concerns surrounding the proposed Made in Europe requirements.

Speaking to Sky News, Reynolds said the governments were “finding a way through” the disagreement, although the precise terms of any compromise remain uncertain.

The negotiations come ahead of the EU–UK summit scheduled for 20 November, when Prime Minister Andy Burnham is due to meet European Commission President Ursula von der Leyen and European Council President António Costa.

For British manufacturers, the immediate issue is whether political promises of closer cooperation can prevent new economic barriers from emerging.

When industrial policy becomes trade policy

The dispute centres on the European Commission’s Industrial Accelerator Act, proposed in March.

The legislation would introduce European-origin and low-carbon requirements into public procurement and certain government support schemes covering strategic industries.

Among the sectors affected are steel, cement, aluminium, automotive manufacturing and technologies associated with the energy transition.

Brussels argues that such measures are necessary to strengthen European manufacturing and reduce dependence on overseas suppliers, particularly in industries exposed to competition from China.

The economic difficulty is that European industrial production does not stop at the EU’s external borders.

British manufacturers supply components, materials and specialist engineering services to European factories, while many UK production facilities rely on parts and technologies imported from the continent.

Automotive manufacturing illustrates the problem.

Vehicles assembled in Britain frequently contain components produced in several EU countries. Equally, European automotive manufacturers incorporate British-made parts into their own production.

If eligibility for subsidies or public contracts depends increasingly on where products and components originate, companies could face incentives to reorganise supply chains.

The question is therefore not merely whether British products can enter the European market, but whether they will qualify for the same industrial support arrangements as competing European products.

France and Germany disagree

The dispute has exposed differences among EU governments.

As EU Today reported earlier this month, France has argued for a restrictive interpretation of European origin requirements, while Germany has favoured a broader approach allowing certain trusted trading partners to participate.

Berlin’s position reflects the interests of industries whose production networks extend beyond the EU, including manufacturers operating in Britain.

According to reporting on the negotiations, France and Germany have discussed a potential compromise under which Britain might receive preferential treatment if it aligns with European tariffs on Chinese goods.

Such an arrangement would have implications extending beyond manufacturing.

It would involve coordination over trade policy towards China, an area in which Britain currently retains independent decision-making authority.

No agreement has been finalised, and any legislative compromise would require approval through the EU’s institutional procedures.

Burnham’s broader European calculation

For Burnham’s government, the industrial disagreement coincides with a wider attempt to redefine relations with Brussels.

The forthcoming summit is expected to concentrate on practical agreements covering agricultural and food trade, emissions trading and temporary mobility arrangements for young people.

A sanitary and phytosanitary agreement could reduce inspections and documentation requirements for certain food products moving between Britain and the EU.

Closer coordination between emissions trading systems could also reduce complications created by different carbon-pricing regimes.

However, these initiatives do not resolve the wider question of Britain’s relationship with the European single market.

Burnham has indicated that he intends to open a broader discussion about future options, while maintaining Labour’s existing commitments against rejoining the single market, customs union or restoring general free movement during the current parliamentary term.

Reynolds has acknowledged that repeated changes in EU policy create uncertainty for British companies operating across the Channel.

The price of industrial cooperation

The underlying difficulty is structural.

Britain seeks the benefits of close industrial integration while maintaining the independence acquired through Brexit. The EU, meanwhile, is increasingly using common industrial rules, subsidies and procurement preferences to pursue economic-security objectives.

These priorities are not necessarily incompatible, but reconciling them may require new arrangements governing regulatory alignment, product origin and relations with third countries.

As EU Today previously examined, London’s request to be treated as a trusted industrial partner has already become part of the broader political negotiations.

The November summit may establish a framework for resolving some immediate concerns.

It will not, however, eliminate the fundamental problem facing British manufacturers: future decisions taken in Brussels can materially affect their competitiveness, even though Britain no longer participates directly in making those decisions.

  •  

EU Lawmakers Move to Relax 2035 Car Emissions Rules as Industry Presses for Greater Flexibility

The European Parliament has taken another step towards revising the European Union’s 2035 vehicle-emissions framework, after lawmakers from three major political groups agreed amendments offering manufacturers greater flexibility in meeting carbon dioxide reduction targets.

The compromise, approved on 22 October by Parliament’s Transport and Industry committees, proposes an 87.5 per cent reduction in average emissions from new passenger cars by 2035, compared with the 2021 baseline. This is less stringent than the European Commission’s proposed 90 per cent reduction and represents a further departure from the existing 100 per cent reduction in tailpipe emissions for new cars and vans.

The changes have not become law. They remain subject to parliamentary procedures and negotiations with EU governments. Nevertheless, the committee agreement shows how concerns over manufacturing competitiveness, production costs and technological choices are reshaping European climate legislation.

A fundamental revision of the 2035 framework

The original 2035 target, adopted in 2023 as part of the EU’s Fit for 55 legislation, required manufacturers to achieve a 100 per cent reduction in average tailpipe carbon dioxide emissions from new cars and vans. It effectively directed the market towards battery-electric and other zero-emission vehicles.

Manufacturers have argued that the transition is taking place under difficult commercial conditions. Competition from Chinese producers, costs of developing new platforms and batteries, and uncertainty over charging infrastructure contributed to demands for regulatory flexibility.

In December 2025, the European Commission responded with an automotive package proposing a 90 per cent reduction requirement by 2035. It would permit manufacturers to compensate for some remaining emissions using mechanisms involving low-carbon steel produced in the EU and qualifying renewable fuels.

The latest parliamentary compromise would lower the target further, to 87.5 per cent, while allowing low-carbon steel credits to count towards compliance. For light commercial vehicles, lawmakers also proposed reducing the 2035 target to 80 per cent and the 2030 target to 35 per cent.

Why low-carbon steel matters

A notable feature of the compromise is the connection between car-emissions rules and European steelmaking. Steel production is a major industrial source of carbon dioxide, and companies face investment requirements to replace conventional production processes with lower-emission alternatives.

Regulatory credits for carmakers using qualifying European low-carbon steel could create demand for cleaner industrial materials and encourage domestic investment. But emissions avoided during production are not equivalent to reductions in exhaust emissions. The accounting mechanism therefore creates a distinction between cutting tailpipe output and compensating for some remaining emissions through materials and manufacturing.

The compromise also connects vehicle rules with a broader industrial-policy debate about European-made products. As EU Today previously reported, vehicle decarbonisation has increasingly become part of the discussion about European industrial competitiveness.

Electric vehicle sales continue to increase

The debate comes despite growth in electric vehicle registrations. According to figures from the European Automobile Manufacturers’ Association, battery-electric cars represented 22.7 per cent of new EU passenger car registrations in the first nine months of 2026, against 16.1 per cent during the same period of 2025.

Approximately 1.93 million battery-electric cars were registered between January and September, with considerable growth in Germany and France. Hybrid-electric vehicles nevertheless remained the largest single powertrain category at 36.3 per cent, while petrol and diesel together represented 28.2 per cent, down from 36.9 per cent a year earlier.

The figures show that electrification is progressing, but combustion engines still account for a substantial share of sales. Manufacturers must make investment decisions across several technologies while anticipating changing legislation.

Disagreements over industrial strategy

The parliamentary compromise follows discussions between France and Germany about the relationship between car-emissions rules and measures favouring European production. Paris has emphasised domestic industrial capacity; Berlin has pressed for greater technological flexibility.

Supporters of looser standards argue that manufacturers need time to adjust investment and respond to consumer demand. Critics warn that weakening the target could delay investments in electric vehicles, batteries and charging networks by making future demand less certain.

The eventual legislation will determine not only which vehicles may be sold after 2035, but also how the EU balances emissions reduction, international competition and the position of its manufacturing industry.

  •  

Audi boss under fire in Germany for Trump rally appearance

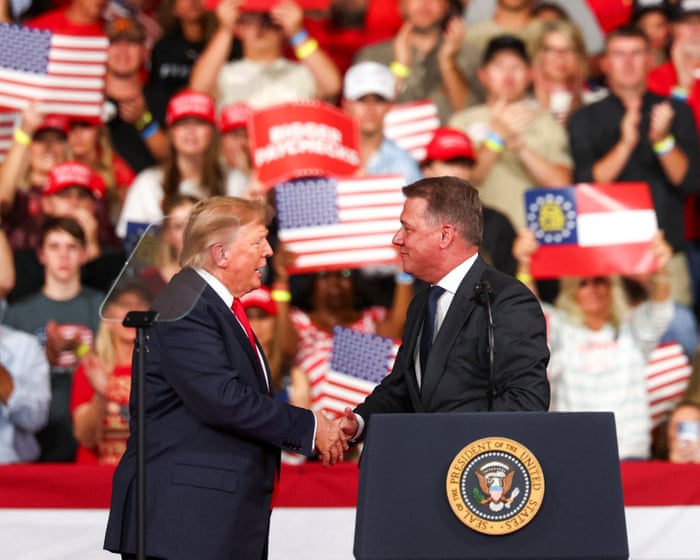
Gernot Döllner criticised for in-person announcement of major investment in US days before midterm elections

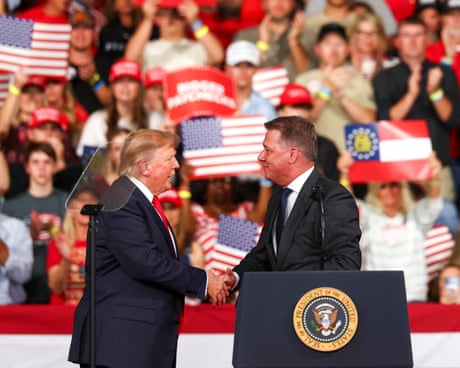
The head of the luxury carmaker Audi is under fire in Germany for appearing at a rally with Donald Trump just days before the US midterm elections, to announce billions of dollars of investment in battleground state Georgia.

Gernot Döllner joined Trump on stage after the US president gave a speech criticised by the head of an elected body of employees at Audi’s parent company, Volkswagen, as being full of “racism, sexism, transphobia [and] contempt for democracy”.

Continue reading...

© Photograph: Edgar Su/Reuters

© Photograph: Edgar Su/Reuters

© Photograph: Edgar Su/Reuters

  •  

Volkswagen to build $4bn Audi SUV factory in US despite job cuts at home

VW investment, creating 4,500 jobs in Georgia, comes amid Trump’s damaging tariffs, intense Chinese competition and costly shift towards EVs

Audi has said it will spend $4bn (£3bn) to build its first factory in the US, as its parent company, Volkswagen, struggles with the impact of steep tariffs imposed by Donald Trump.

The German brand’s chief executive, Gernot Döllner, joined Trump on stage at a campaign rally on Saturday night to announce the factory in Macon, Georgia, in an unusual move by a big European brand just days before the US midterm elections.

Continue reading...

© Photograph: Friso Gentsch/EPA

© Photograph: Friso Gentsch/EPA

© Photograph: Friso Gentsch/EPA

  •  

The EU’s Climate Agenda is Running on Empty – and the UK isn’t Far Behind

France and Germany have teamed up to press the EU to relax its looming combustion car ban. It’s the latest sign the EU's climate agenda is running on empty, says Ben Pile – and the UK isn't far behind.

The post The EU’s Climate Agenda is Running on Empty – and the UK isn’t Far Behind appeared first on The Daily Sceptic.

  •  

Electric Car Sales Surge 70 Per Cent as France and Germany Seek Changes to EU Emissions Rules

Registrations of fully electric cars across 17 European markets increased by 70.3 per cent in September, according to industry figures published on Monday, 19 October, as France and Germany seek to ease the European Union’s emissions requirements for new vehicles.

The data show that 300,202 battery-electric cars were registered during the month, accounting for 32.6 per cent of new passenger-car registrations in the markets surveyed.

The figures emerge three days after Paris and Berlin announced a joint position on the future of Europe’s automotive industry, proposing greater flexibility in the EU’s 2035 emissions regime while introducing measures intended to favour vehicles manufactured in Europe.

Electric vehicles gain market share

The latest figures, compiled by E-Mobility Europe, New Automotive and Fier Automotive, indicate that electric vehicle demand accelerated sharply during September.

According to the industry data published on 19 October, approximately 1.98 million battery-electric cars have been registered across the 17 markets during the first nine months of 2026, an increase of 38.1 per cent compared with the equivalent period last year.

Higher oil prices, government incentives and the introduction of more affordable electric models have all contributed to demand.

The figures represent a substantial change in the composition of European new-car sales, although they cover selected markets rather than constituting a complete statistical account of the EU’s 27 Member States.

France recorded 65,243 battery-electric registrations in September, representing 41.7 per cent of its new-car market. Germany registered 88,724 electric vehicles, giving the technology a market share of 34.6 per cent.

Both countries have substantial automotive manufacturing industries and are directly involved in negotiations over Europe’s future emissions legislation.

Significant differences between European markets

Despite the overall increase, electric vehicle adoption remains uneven across the continent.

Norway retained its position as Europe’s most electrified new-car market, with battery-electric vehicles accounting for 98.8 per cent of registrations in September.

Denmark followed with 88.8 per cent, while Finland recorded 62.7 per cent and Sweden 49 per cent.

Electric models also accounted for approximately half of new-car registrations in Belgium, the Netherlands, Ireland and Portugal.

At the other end of the market, battery-electric vehicles represented only 11.2 per cent of registrations in the Czech Republic, 7.6 per cent in Italy and 6.2 per cent in Poland.

These differences illustrate the difficulty of establishing a uniform European transition timetable.

Household incomes, purchase incentives, vehicle prices and charging infrastructure differ substantially between countries. The availability of affordable electric cars is particularly important in markets where buyers are more sensitive to the initial purchase price.

The varying national figures also complicate the EU’s industrial calculations, since manufacturers must operate across markets progressing at different rates.

France and Germany reach automotive compromise

On 16 October, French President Emmanuel Macron and German Chancellor Friedrich Merz agreed on a joint approach to changes in European automotive regulations.

Under the proposed compromise, car manufacturers would be required to reduce carbon dioxide emissions from new vehicles by 90 per cent by 2035 compared with the 2021 reference level.

The agreement would also remove a proposed requirement to compensate for the remaining emissions through measures such as the use of low-carbon steel.

The change would create additional opportunities for manufacturers to continue selling vehicles powered by combustion engines beyond 2035, subject to the final legislative framework.

In their joint declaration on the automotive industry’s future, the French and German governments argued that emissions reduction must be combined with industrial competitiveness, investment and European manufacturing capacity.

The agreement also envisages preferential treatment for vehicles produced in Europe under certain public procurement and subsidy arrangements.

Britain could potentially benefit from provisions allowing selected European partners to qualify under the proposed industrial framework.

The Franco-German understanding is not, however, a final EU legislative decision. Changes to the regulatory regime require agreement through the relevant European legislative procedures.

Automotive competitiveness enters the debate

The principal argument advanced by supporters of greater regulatory flexibility is that European manufacturers need additional time to adapt production, protect employment and compete with international rivals.

German manufacturers retain extensive investment in combustion-engine and hybrid technology, while French producers have placed considerable emphasis on electric vehicles and maintaining European supply chains.

The negotiations therefore concern more than emissions limits. They also involve battery production, access to raw materials, manufacturing costs and the ability of European companies to compete with producers in China and other markets.

Supporters of the existing transition timetable argue that weakening long-term requirements could discourage investment in electric manufacturing capacity just as consumer demand is increasing.

Manufacturers seeking greater flexibility maintain that regulatory targets must account for uneven market conditions and the cost of developing new technologies.

September’s sales figures provide evidence that electric vehicle adoption is accelerating, but they do not establish whether the same rate of growth will continue without existing incentives.

The debate now centres on whether regulatory relaxation will preserve Europe’s automotive industry during the transition or slow investment in the technology that is already capturing an increasing share of the market.

  •  

Mercedes Chief Warns EU Against Excluding Britain from ‘Made in Europe’ Industrial Rules

Mercedes-Benz chief executive Ola Källenius has warned that excluding British manufacturers from European industrial preference rules would damage automotive production on both sides of the Channel, increasing pressure on Brussels ahead of negotiations over its proposed Industrial Accelerator Act.

The head of Mercedes-Benz has warned that excluding British manufacturers from the European Union’s proposed industrial preference rules would damage the competitiveness of carmakers across Europe, challenging Brussels over legislation intended to protect European production from growing international competition.

Ola Källenius, chief executive of Mercedes-Benz and president of the European Automobile Manufacturers’ Association (ACEA), criticised the prospect of restricting British participation in the forthcoming “Made in Europe” framework during discussions in Brussels on Wednesday, 14 October.

His intervention comes as European governments negotiate the Industrial Accelerator Act, which would introduce European-content requirements affecting public procurement and certain forms of industrial support.

The proposed legislation is intended to strengthen manufacturing within the EU, but its treatment of production in neighbouring countries has become contentious, particularly in an automotive industry whose factories and suppliers operate across national borders.

European production extends beyond the EU

British manufacturing remains closely integrated with continental European automotive production despite the United Kingdom’s departure from the single market.

Components manufactured in Britain are incorporated into vehicles assembled in EU member states, while British factories depend on engines, batteries, electronics and other parts produced in continental Europe.

The value of this integrated manufacturing system depends on companies being able to source components across borders without unnecessary restrictions.

Källenius warned that excluding the UK from the proposed rules would weaken manufacturers operating on both sides of the Channel.

His position reflects industry concerns that a narrowly defined European-content regime could impose additional costs on companies already facing pressure from Chinese competition, slowing demand and substantial investment requirements.

As EU Today reported in September, British Prime Minister Andy Burnham has been pressing Brussels to recognise the UK as a trusted industrial partner under the emerging framework.

Germany has also supported a broader approach that would allow selected trading partners to qualify under European-content rules where reciprocal conditions are met.

France has favoured stronger preferences for production within the EU itself, reflecting differences among member states over how far European industrial policy should extend beyond the Union’s borders.

A dispute over industrial sovereignty

The Industrial Accelerator Act proposed by the European Commission is intended to strengthen Europe’s manufacturing base and support production in strategically important sectors.

Its provisions address public procurement and industrial incentives affecting products including vehicles, steel, aluminium and clean technologies.

The Commission wants European public spending to support local industrial capacity rather than reinforce dependence on imports from major international competitors.

China has become the principal focus of those concerns because of its expanding manufacturing capacity, particularly in electric vehicles and batteries.

However, measures designed to counter Chinese industrial competition could also affect established trading partners whose manufacturers form part of European supply chains.

The United Kingdom, Norway, Switzerland and Turkey occupy different legal positions in their economic relations with the EU, but all maintain important industrial connections with member states.

An approach that treats their production as equivalent to imports from countries with substantially different market conditions could require European companies to reorganise existing supplier relationships.

For manufacturers, replacing a supplier may involve more than simply ordering components from another factory. Production standards, technical certification, logistics and long-term investment arrangements can make changes expensive and difficult.

Industry demands regulatory certainty

Following an ACEA board meeting on Wednesday, European manufacturers called for faster progress on the wider automotive legislative package.

In its 14 October statement, ACEA urged EU institutions to advance negotiations so that the package could be finalised early next year.

The association argues that manufacturers require a predictable regulatory framework to plan investments in electric vehicles, production facilities and new technologies.

Källenius linked the industry’s transition towards zero-emission mobility with the need to preserve employment and strengthen economic security.

European manufacturers are simultaneously investing heavily in electrification while competing against Chinese companies with established battery supply chains and significant production capacity.

The resulting financial pressures are particularly serious for manufacturers that must develop new vehicle platforms while maintaining existing factories and dealer networks.

Additional restrictions on component sourcing could complicate those decisions at a time when companies are seeking to reduce costs.

Britain refuses to follow EU tariffs automatically

The dispute has acquired a further dimension following remarks by British Business Secretary Jonathan Reynolds.

Speaking on Wednesday, Reynolds indicated that Britain would not automatically follow the European Union in imposing tariffs on Chinese vehicles.

The UK government maintains that trade measures must be determined according to British economic interests rather than adopted simply to align with Brussels.

That position complicates London’s attempt to secure favourable treatment under European industrial rules.

EU policymakers have argued that closer alignment on trade defences could support Britain’s claim to be treated as a trusted partner.

British ministers, however, must consider whether restrictions on Chinese imports would benefit domestic manufacturers and consumers.

The disagreement will form part of the broader economic relationship being discussed ahead of the next UK–EU summit, scheduled for 20 November.

The wider implications for EU–UK relations

The automotive dispute follows earlier negotiations over British participation in European defence procurement and other industrial programmes.

In both cases, London wants access to initiatives designed to strengthen European production while remaining outside the EU’s institutional framework.

Brussels must determine how far preferential treatment can extend to non-member countries without undermining the objectives of its industrial policy.

The Commission’s proposals have already revealed disagreements between governments favouring a tightly defined European manufacturing base and those seeking to preserve wider commercial partnerships.

Källenius’s intervention strengthens the argument that industrial protection cannot be considered separately from the supply chains on which European manufacturers depend.

The final legislation will influence investment decisions, procurement arrangements and the position of British suppliers within the continental automotive industry.

The outcome will also provide an indication of how far the EU is prepared to accommodate its closest trading partners as it attempts to strengthen European manufacturing against growing competition from China.

  •  

EU Caps Chinese Hybrid Car Imports at 350,000 as Brussels Moves to Protect Europe’s Motor Industry

The European Union has reached an agreement with China to restrict imports of Chinese hybrid vehicles to 350,000 annually, introducing a significant new barrier to the expansion of Chinese manufacturers in Europe’s automotive market.

The arrangement, confirmed on 12 October, follows months of negotiations between Brussels and Beijing and reflects growing concern about the competitive position of European carmakers.

The import ceiling could reduce Chinese hybrid vehicle sales in the EU by more than half compared with previously anticipated volumes, although the actual effect will depend on demand, product classifications and implementation.

The agreement comes as manufacturers gather for the Paris Motor Show, where the future of European vehicle production, Chinese competition and industrial policy have become central subjects.

China’s Commerce Ministry has presented the outcome as a negotiated arrangement intended to preserve trading relations, while the European side has emphasised the need to prevent rapidly increasing imports from undermining domestic production.

Chinese manufacturers confront a new European barrier

Chinese carmakers have expanded aggressively in overseas markets as domestic demand has weakened. Chinese passenger vehicle exports rose sharply in September, with manufacturers increasingly targeting Europe, Latin America and Asian markets.

Hybrid vehicles have become particularly important because they offer consumers lower fuel consumption without requiring the same degree of dependence on charging infrastructure as fully electric cars.

This has allowed Chinese brands to compete in market segments where European manufacturers retain substantial established production capacity.

The new quota limits the number of eligible Chinese hybrid vehicles permitted to enter the European market each year. According to details of the import restrictions, shipments exceeding the permitted volume would face restrictions at EU customs.

The mechanism differs from a conventional tariff because imports beyond the ceiling cannot simply enter the market by paying a higher duty. Manufacturers and importers will need to consider both delivery costs and the availability of import allocations.

European manufacturers seek protection

The measures arrive amid growing pressure on the European automotive industry, which faces high production costs, expensive energy, competition from Chinese manufacturers and the capital requirements of shifting towards electrified transport.

Companies operating in Germany, France, Italy and other established manufacturing centres must fund the development of new vehicles while maintaining existing factories and employment.

Chinese manufacturers benefit from extensive domestic production networks, considerable scale and access to battery manufacturing capacity.

European policymakers have questioned whether competition takes place under equivalent economic conditions, particularly where Chinese producers receive support from state-directed industrial policies.

Beijing rejects allegations that its export performance results principally from unfair state assistance, arguing that Chinese companies have achieved competitiveness through investment, innovation and efficiency.

The quota represents a departure from the assumption that European consumers will necessarily have unrestricted access to the lowest-priced imported vehicles.

Its economic effects will depend partly on whether European manufacturers can use the additional protection to improve productivity and develop more competitive models.

Will Chinese manufacturers move production into Europe?

Restrictions on imports do not necessarily reduce the presence of Chinese-owned companies in the European automotive industry.

Several manufacturers are already developing production capacity outside China, including within the European Union. BYD’s investment in Hungary is one example of how Chinese companies can pursue access to European consumers through local manufacturing rather than relying entirely on imported finished vehicles.

The new arrangements could strengthen the commercial incentive to expand such operations.

For European governments, Chinese investment presents a difficult calculation. New factories may create employment, increase industrial activity and preserve automotive supply chains, while also expanding the influence of Chinese manufacturers within Europe’s domestic market.

The economic consequences depend on how much research, component manufacturing, battery production and other high-value activity takes place locally.

A Chinese-owned assembly plant using predominantly imported components would provide different benefits from a fully developed European production network.

The British dimension

The debate is also drawing attention to the position of the United Kingdom, whose automotive industry remains closely integrated with European supply chains despite Brexit.

Executives from Stellantis and Renault have supported including Britain within proposed European industrial protection measures, reflecting the importance of UK manufacturing operations to their broader businesses.

Such an arrangement would raise questions about regulatory alignment, trade preferences and the conditions under which non-EU production could qualify for European industrial support.

British manufacturers also face the challenge of Chinese competition, and decisions taken in Brussels could influence investment strategies across the wider European automotive sector.

Protection versus competitiveness

The restrictions may offer European manufacturers additional time to adapt, but they do not eliminate the structural challenges confronting the industry.

Energy prices, labour costs, the availability of batteries and the affordability of new vehicles remain important factors in the competitiveness of European production.

Nor will the quota necessarily prevent Chinese firms from gaining market share through investment, partnerships or vehicles manufactured outside China.

The EU’s approach combines restrictions on imports with the possibility of continued Chinese industrial participation inside Europe.

The outcome will depend on whether European manufacturers use the reduced competitive pressure to strengthen their technological and manufacturing position, or whether the restrictions primarily accelerate the relocation of Chinese-owned production into the EU.

  •  
❌