❌

Reading view

Peter Pan Tariffs for Companies That Never Grow Up
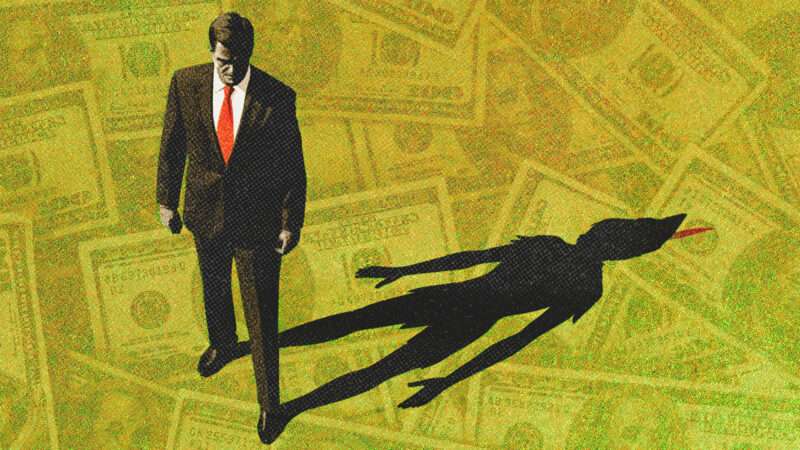
A green tinted background of U.S. paper money with a businessman standing on it who has a shadow that looks like Peter Pan | Illustration: Patrick Bryk/Dreamstime./Midjourney

Of all the arguments for protectionism, the infant industry argument probably has the strongest theoretical appeal. By protecting a new industry from its more developed foreign competition, the story goes, tariffs give domestic producers the time to grow, learn, and become efficient enough to stand on their own. Domestic consumers feel the short-term pains of higher prices, but they enjoy the long-term gains of job growth and lower prices as the new industry blossoms.

It's no secret that tariffs have driven significant price increases over the last year and a half. A study from the New York Federal Reserve finds that tariffs "contributed 2.9 percentage points to goods price inflation" and that without tariffs those prices would have slightly declined. Tariff defenders, looking for a new reason to claim these higher prices are only temporary, have reimagined the infant industry argument. Now it's being used to support trade barriers in industries that are over a century old, but the promise is exactly the same: Domestic firms need the protection so they can compete, innovate, and cut costs until prices come back down even further than they were before the tariffs.

Michael Brendan Dougherty recently made such an argument in National Review, arguing that "tariffs can, over time, bring prices below where they started." When economist Don Boudreaux called the argument "bizarre," Dougherty replied that critics had failed to acknowledge the dynamic process by which markets respond to tariffs "by adapting and cutting costs." Although he is light on specific details, he posits that the changed incentives of a "paradigm shift" in tariff policy will spur domestic competition, leading to the theorized price reduction. Of course, firms would still respond to the dynamic processes of domestic competition without a tariff wall, but the point stands.

From there, the reworked infant industry argument becomes the standard version advanced more than two centuries ago by Alexander Hamilton and his disciple Friedrich List. When Hamilton made this claim in 1791, his argument may have seemed suitable for a new nation seeking to firm up its economy and security against established European powers.

Others at the time pointed out that special interest groups—a manifestation of the "violence of faction" so thoroughly dissected in the Federalist Papers—had already begun to coalesce around the fledgling iron industry in Pennsylvania, clamoring for protective tariffs. Two years earlier, James Madison had warned about a "premature policy of stimulating manufactures" driving tariffs too high. In the end, Hamilton recommended and Congress enacted a far more moderate tariff schedule than his theoretical musings portended. American iron manufacturers received a consolation prize of a higher tariff on their competitors than the rate for most general imports. Hamiltonians have been touting the infant industry argument ever since.

Nearly 250 years later, those same infants apparently have yet to advance into adulthood. Steel, the direct successor to the founding-era iron manufacturers, remains a singular focus of President Donald Trump's protectionist tariff policies, just as it was under former President Joe Biden. And former President George W. Bush before him. Indeed, steel has been a recurring beneficiary of protectionism for most of America's existence.

This extended period of protectionist infancy suggests that the argument needs a new name. We propose the "Peter Pan industry argument" for companies that never grow up because tariffs make sure they never have to.

The question tariff advocates rarely ask is: Why do some American producers have higher costs than foreign rivals even in the face of lower-cost foreign competition? The answer comes down to specific rules and choices within particular firms and industries. Tariffs, and protectionism in general, address none of these. No industry illustrates this like steel, but it is far from the only one.

In 1947, United Steelworkers won a contract provision known as Section 2-B. Among other things, this barred mill managers from changing established work practices unless new technology required it. Steel companies tried to get rid of this in 1959, finding it difficult (given union incentives) to establish that technology required change. In response, 500,000 steelworkers went on strike for 116 days. This strike sent buyers abroad, causing 1959 to be the first year the U.S. imported more steel than it exported. One of the then-new technologies that was delayed was basic oxygen furnaces, which could produce steel far faster and cheaper than the open-hearth furnaces that were so common. In 1965, only about 17 percent of steel made in the U.S. was made using the basic oxygen furnace. Japan produced 55 percent of its steel with this faster, more efficient method.

Change finally came from a steel customer. Vulcraft, a maker of steel joists, grew tired of paying Big Steel's prices and waiting for Big Steel's deliveries. In 1969, free from steel unions and preconceived notions, the company looked for new steel-producing technologies and found the answer in the electric arc furnaces that had been adopted in much of the world throughout the 1950s and '60s. Vulcraft's parent company later renamed itself Nucor, and minimills like the ones it pioneered now make most of America's steel.

So the modern steel industry was built by a frustrated steel buyer who found a way around protected companies. In other words, the U.S. steel industry has lagged behind the technologies found around the world.

We could go on, but the broad point here is that the "relatively higher domestic production costs that made the tariff 'necessary' in the first place," as one critic put it, are often the result of preventing competition in the first place. It's odd to suggest that further preventing competition through tariffs will somehow alleviate the ills of already-prevented competition.

Tariff advocates fail to acknowledge that the ability to import steel also comes with the benefit of access to cheaper steel for steel-using industries, such as manufacturing. A 50 percent tariff on steel further closes the release valve that imported steel offers. Buyers of steel are then left to purchase more of the more expensive domestic steel. Because new steel mills take years to bring online, this causes delays and longer delivery times for manufacturers.

We don't have to wonder what happens when a country lowers its tariffs on materials used by manufacturers. India did this in the '90s, and researchers found that newly available inputs accounted for 31 percent of the new products that Indian manufacturers introduced. And what happens when the U.S. imposes tariffs on steel? Downstream U.S. firms become less competitive. This is why American businesses clamor for exemptions to tariffs, especially for tariffs on materials like steel.

Perhaps all this could be forgiven if tariffs advanced national security concerns, as tariff advocates assert. They point out that an adversarial nation could cut off supplies of critical materials during wartime and cripple America's ability to defend itself. Unfortunately, tariffs fail there too.

First, this conflates production with access. While domestic production does ensure domestic access, access can be secured without production. In the case of steel, the Commerce Department reports that in 2025, the U.S. imported steel from 79 countries, with Canada being our top foreign supplier. The top 10 sources of steel are responsible for 77.8 percent of America's steel imports. None of those countries were considered adversaries—at least not until the tariff crusades pushed these friends away. What's more, according to the American Iron and Steel Institute, only 23 percent of finished steel in the U.S. was imported in 2024. Far from being exposed to foreign states' whims, American access to steel is incredibly resilient.

Second, this view ignores the positive effects of trade and globalization on national security. The Center for Strategic & International Studies finds that increased trade between countries reduces the likelihood that they'll go to war against one another. Globalization helps ensure that domestic access continues unabated should war break out, thanks to the diversity of trading partners.

When Hamilton made the infant industry argument, he at least assured us that the industry would at some point advance to adulthood and stand on its own. Steel, like so many other Peter Pan industries, has proven Madison right. These industries have refused to grow up, and it's time to stop pretending that tariffs will fix that.

The post Peter Pan Tariffs for Companies That Never Grow Up appeared first on Reason Magazine.
  •  

One year of Ukrainian arms exports, and industry has questions: how much army gained, where Berlin office is, who joins joint ventures

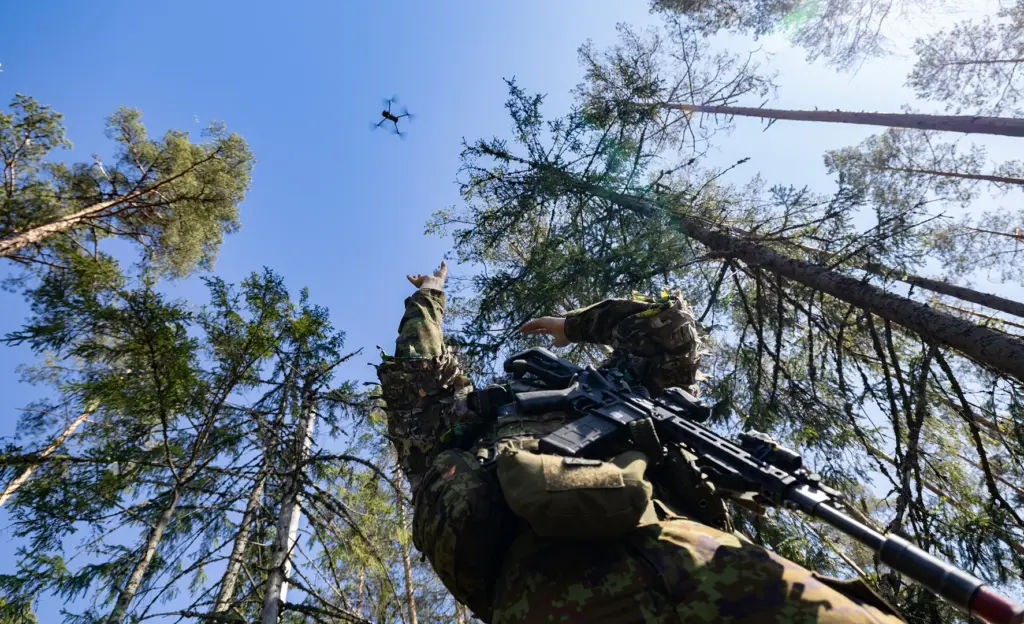
Estonian and Ukrainian soldiers fly drones together during Exercise Hedgehog 2025 in Estonia, where Ukrainian operators were credited with knocking out two battalions in a simulated engagement. Photo: vbl/OR-7 Ardi Hallismaa/ERR

Ukraine now builds far more weapons than it can afford to buy. A year ago, it promised to sell the surplus abroad and turn the proceeds back into its own army. However, 12 months later, that promise has barely materialized: a state fee of up to 30% is pricing Ukrainian arms out of foreign markets, and no one can say how much the army has actually gained, said Ihor Fedirko, executive director of the Ukrainian Council of Armorers.

President Volodymyr Zelenskyy announced the resumption of controlled weapons exports in October 2025, resting it on four promises: 1) sell what Ukraine makes beyond its own needs, 2) channel part of the proceeds into a special fund for the army, 3) open export offices in Europe and the US, and 4) establish joint ventures abroad.

The surplus is real: Ukraine's defense output is projected to reach $55 billion in 2026, far beyond what the state can finance. A year on, Fedirko checked each promise in turn.

1) Export of surpluses: rules that strangle businesses

    On 1 July 2026, the government approved rules for controlled arms exports. They shortened the maximum application review period from 90 to 30 days, but also introduced an export fee: 20% for finished products and technologies, and 30% for components. For finished products exported under the special procedure, the contract value must be at least $334,000.

      In September, the Ukrainian Council of Armorers, together with other associations, proposed a zero rate, no advance collection of the fee, refunds for deals that fall through, and simplified test shipments. The industry was promised that its amendments would be taken into account and that the resolution would be rewritten.

      Even in early October, however, the rules still needed work. According to Fedirko, the new mechanism has effectively not started working. Whether it can bring in additional funds for defense depends on how acceptable the export terms are to manufacturers.

      Fedirko says, though, that judging by current decisions, the state intends to keep the export fee.

      “The industry is ready to discuss its contribution to defense financing. But the rate must be economically justified,” he says.

      2) Procurement for the Ukrainian military: balance is only being established

      He adds that the Ukrainian Council of Armorers intends to push for a rate significantly lower than 20%, one that would let companies fulfill contracts and invest in production.

      With such high rates, Fedirko says, the competitiveness of Ukrainian weapons on foreign markets is in question, as is the ability to send even small test batches to potential buyers.

      “The fundamental requirement is post-payment: after the contract has actually been fulfilled and the manufacturer has been paid. A company should not pay the state in advance a share of income it has not yet received,” he says.

      He added that, given all this, the real export figures remain unclear, as does how much exports have actually brought the military.

      “The military and manufacturers must feel the benefit of exports. I sincerely hope that next year will bring much better results,” he says.

      In addition, on 12 October, the Ukrainian Parliament passed bill No. 15400 in the first reading. It provides for crediting the export fee to a special fund directed to the Ministry of Defense: 50% for the procurement, modernization, and repair of weapons and equipment, and 50% for the pay of Armed Forces personnel.

      The bill has not yet been adopted, but Fedirko says he expects “final adoption and launch of the mechanism.”

      3) Export offices: offices in Germany and Denmark

      On 3 November, the Ukrainian government named the first cities for export offices: Berlin and Copenhagen. On 15 December, it again spoke of preparing an office in Berlin. In reality, Fedirko says he does not know the office’s status, and it likewise remains unclear how companies can apply to it and how many contracts it has helped close.

      4) Joint ventures abroad: There are concrete results in this area

      According to Fedirko, eight joint ventures have been created, five of which are already supplying products to Ukraine. He stresses that this is the result of work by Ukrainian companies, foreign partners and the state, and that it deserves recognition.

      As early as February 2026, the authorities spoke of plans to create ten joint ventures in Europe within a year. At the same time, they announced Quantum Frontline Industries in Germany, with a planned annual capacity of 10,000 drones for Kyiv.

      Beyond the number of ventures and deliveries, however, it is important to understand how other manufacturers can join the Build with Ukraine program.

      “Who accepts applications, by what criteria are decisions made, and what support does a company receive?” Fedirko asks.

      In other words, joint ventures are already delivering results, but the rules of participation and the state support mechanism must be clear to companies that want to develop production abroad.

      •  

      How a Legal Backlash Against Big Tech Is Forcing Big Changes

      A series of lawsuits has created a new de facto regulatory regime as courts order companies like Meta and Google to change their business practices — and pay up.

      © Gabriela Bhaskar/The New York Times

      Meta’s chief executive, Mark Zuckerberg. On Wednesday, a New Mexico judge ordered Meta to pay a record $25 billion penalty for abusing consumer privacy.
      •  

      Inside the institution where Ukraine races to counter Russia's evolving drones

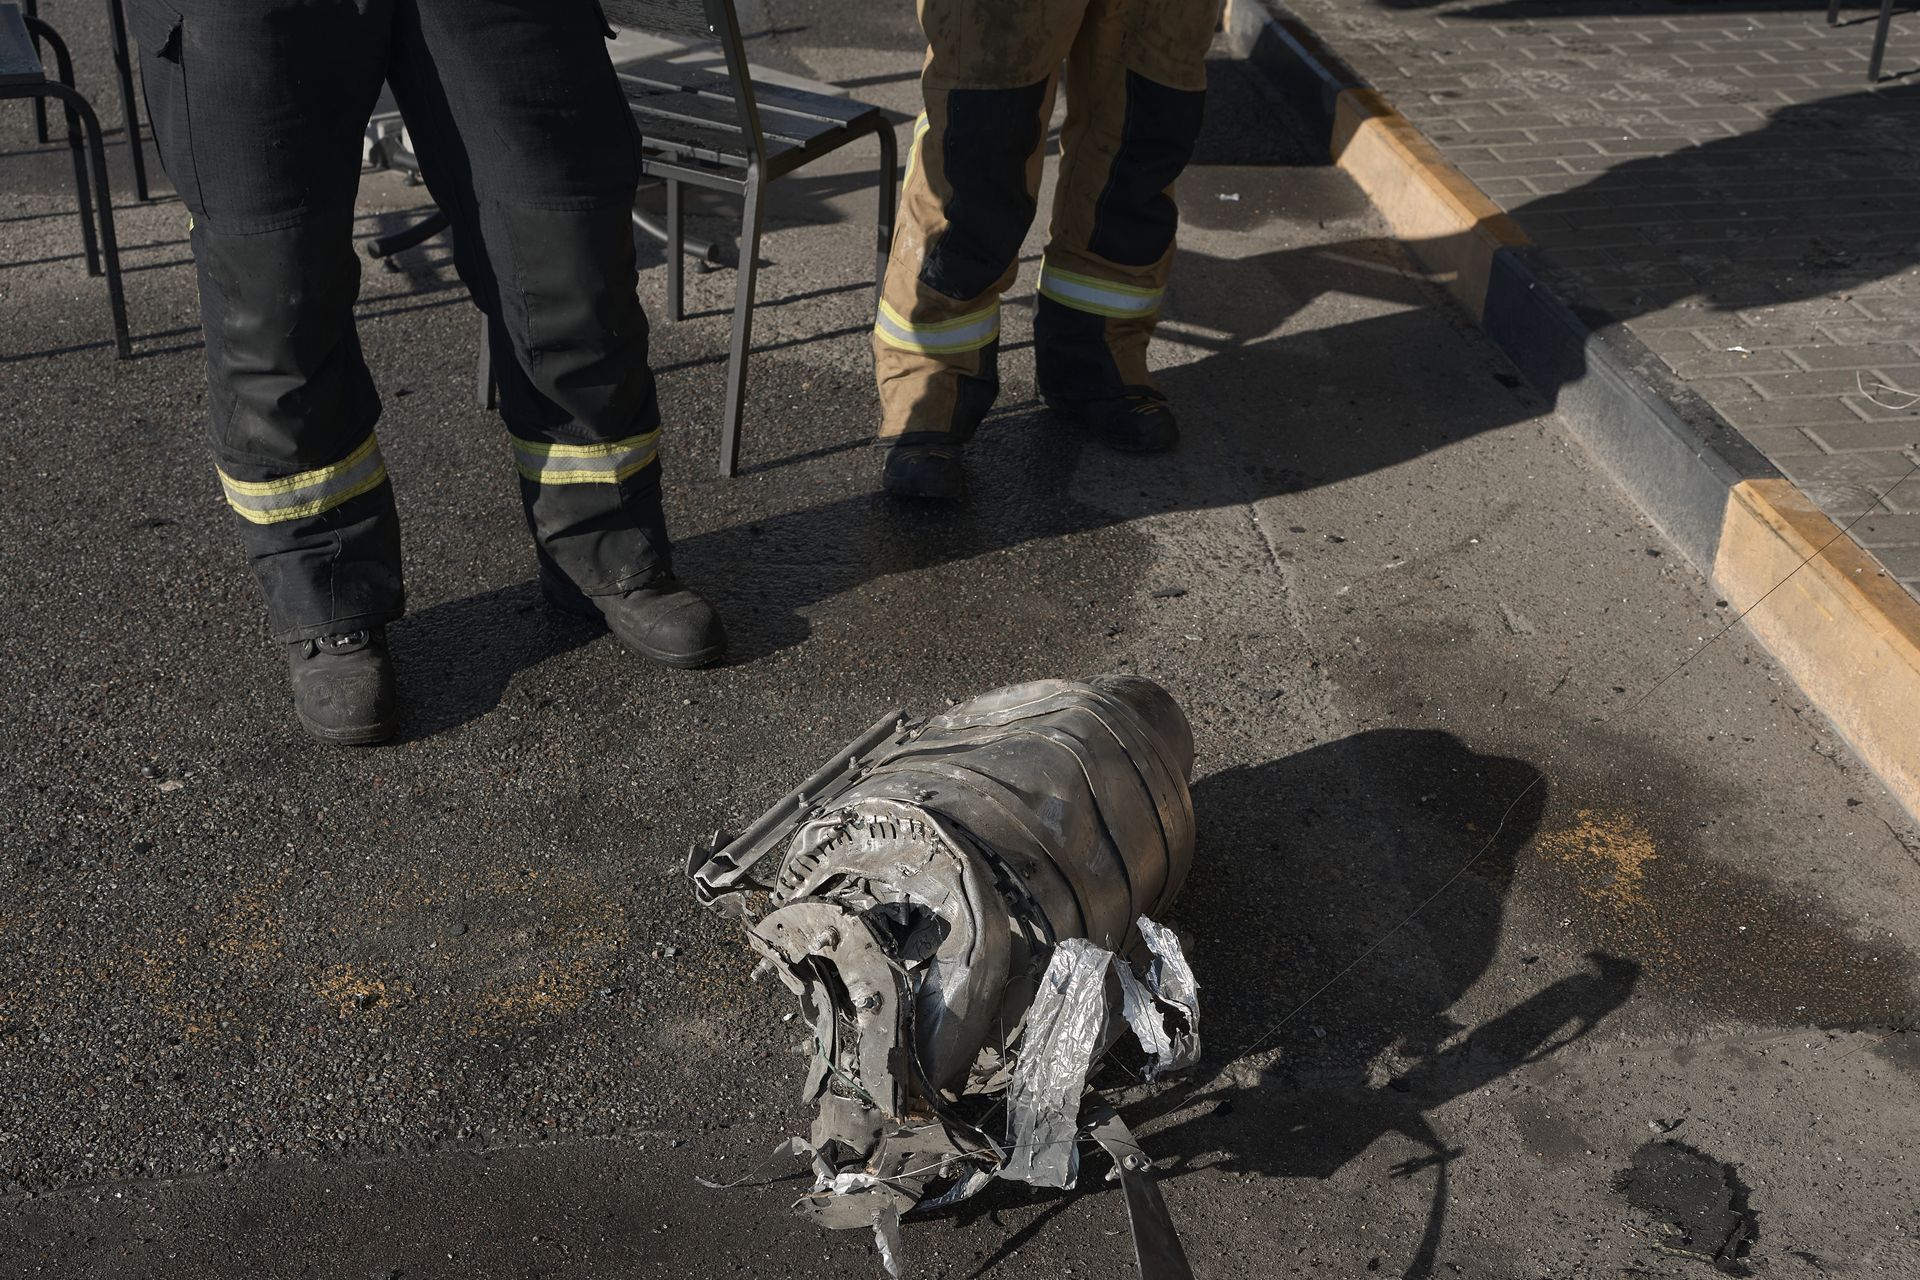
      In a government office, researchers of drones and electronic warfare gather around a small metal device recovered from a Russian Geran drone. Its purpose —  to measure the Earth’s magnetic field for navigation.

      "This is the most recent component we found, about a week or two

      •  

      35 US parts, a Chinese navigation unit, a Russian engine: what’s inside Russia’s Filin missile

      Filin cruise missile

      Ukraine’s military intelligence (HUR) published a 3D model and parts list of Russia’s new Filin cruise missile on 22 October. The breakdown names the Russian companies behind the missile and the foreign makers of its electronics.

      HUR runs its War&Sanctions portal to trace such parts back to their makers. Its stated aim is to “deprive the aggressors of the ability to produce weapons for terror,” the portal says. Meanwhile, Russia is betting on cheap, fast cruise missiles, Serhii Beskrestnov, a freelance adviser to the president on technology, told Radio NV in mid-September. Naming the Banderol, Dan-T, Dan-M, and Gerbera-5, he warned they would soon outrun Ukraine’s jet-powered interceptors, so Ukraine needed its own cheap missiles to shoot them down.

      Composite body, ground launch

      JSC NPO Molniya, part of Russia’s Tactical Missiles Corporation, builds the Filin, HUR said. The agency called it part of a Russian defense-industry trend toward cheap jet-powered, ground-launched air-attack weapons. Russia began firing it at Ukraine in late summer 2026.

      Filin cruise missile components.
      Filin cruise missile components. Image: War&Sanctions

      HUR’s data puts the carbon and fiberglass fuselage at 3.5 m, with a 3 m wingspan. Some parts are 3D-printed. Russia claims a top speed of 800 km/h. The range is 600–1,200 km, and the missile flies at ultra-low altitude or up to 6 km. Versions carry 50-kg or 100-kg warheads. A solid-fuel booster fires it from a ground launcher.

      A firm tied to a Shahed-type drone

      PLAZ LLC makes the onboard equipment, HUR said. The firm also helps produce the Garpiya, a version of Russia’s Shahed-type Geran-2 drone. Filin and Garpiya units share a similar layout and markings. Guidance combines a Chinese-made inertial navigation system with a 16-channel Kometa anti-jamming module from Russia’s VNIIR-Progress.

      The electronics resemble those in other Russian missiles and drones but carry a larger share of Chinese parts. Of 81 components, 35 are American and 22 Chinese. The engine, however, is Russian: an R500 turbojet from Reynolds LLC. A similar engine earlier turned up in the S-71K Kover aviation cruise missile and S-71M Monokhrom, HUR said.

      For comparison, Ukraine found more than 20 foreign components in a different cheap missile, the Banderol, in May 2025. They included 10 US microchips, and the Banderol flies on a Chinese jet engine.

      •  

      Big pharma accused of ‘free-riding on nature’ as global fund attracts just $7,000

      The Cali Fund, set up to raise $1bn a year for biodiversity from drug companies, remains near empty

      Big pharmaceutical companies have been accused of “free-riding on nature”, after a landmark biodiversity fund that invites businesses to put some of their profits back into conservation was left virtually empty.

      The Cali Fund set out to raise $1bn (£750m) annually, by asking companies that profit from nature’s genetics to contribute towards conservation in low-income countries. But more than 18 months after the fund was launched, it remains far below this target.

      Continue reading...

      © Photograph: Rebecca Cole/The Guardian

      © Photograph: Rebecca Cole/The Guardian

      © Photograph: Rebecca Cole/The Guardian

      •  

      The EU’s Climate Agenda is Running on Empty – and the UK isn’t Far Behind

      France and Germany have teamed up to press the EU to relax its looming combustion car ban. It’s the latest sign the EU's climate agenda is running on empty, says Ben Pile – and the UK isn't far behind.

      The post The EU’s Climate Agenda is Running on Empty – and the UK isn’t Far Behind appeared first on The Daily Sceptic.

      •  

      EU Carbon Market Deal Raises Reserve Limit as Industrial Pressure Mounts

      European Union negotiators have reached a provisional agreement to revise the rules governing the bloc’s carbon market, increasing the number of emissions allowances that can remain in reserve before being permanently cancelled.

      The agreement, reached by the Council and European Parliament on 20th October and announced the following day, raises the invalidation threshold of the EU Emissions Trading System’s market stability reserve from 400 million to 700 million allowances.

      The compromise reached by EU negotiators follows months of pressure from energy-intensive industries concerned about carbon prices, electricity costs and competition from manufacturers operating under less restrictive environmental regimes.

      The measure requires formal approval before entering into force and forms part of a wider review of the EU’s principal carbon-pricing mechanism.

      A larger reserve for future market disruptions

      Established in 2019, the market stability reserve was designed to address the accumulation of surplus emissions allowances that had weakened the effectiveness of Europe’s carbon market.

      Under the Emissions Trading System, companies in covered sectors must surrender allowances corresponding to their greenhouse gas emissions. The total quantity available is progressively reduced, creating a financial incentive to cut emissions.

      The reserve adjusts the supply of allowances entering the market, withdrawing them when there is a substantial surplus and releasing them under specified conditions when supply becomes scarce.

      Existing rules also provide for the permanent cancellation of allowances held above a threshold of 400 million.

      Under the new agreement, that threshold would increase to 700 million, allowing a larger stock to remain available for potential future release.

      The change does not automatically introduce 300 million additional allowances into circulation. Releases would continue to depend on the reserve’s operating rules and market conditions.

      According to the Council, more than three billion allowances have been invalidated since the mechanism began operating in 2023.

      The Commission initially proposed ending automatic invalidation indefinitely, while the Council’s September negotiating position envisaged a temporary suspension followed by a higher threshold.

      The compromise retains invalidation but increases the amount protected from cancellation.

      Industry competitiveness enters climate negotiations

      The agreement follows growing concern about the cumulative cost of European climate regulation, particularly for steelmaking, chemicals, cement and other energy-intensive sectors. Manufacturers have warned that carbon costs, combined with relatively expensive electricity and industrial gas, complicate investment decisions and weaken their ability to compete internationally.

      Brussels must also consider the consequences of production shifting to jurisdictions with lower emissions-related costs, a phenomenon known as carbon leakage. Earlier this year, EU Today examined the Commission’s consideration of changes to industrial protections under the ETS, including the relationship between free allowances and the Carbon Border Adjustment Mechanism.

      The latest reserve agreement does not directly change the allocation of free allowances, the emissions cap or the obligations imposed on individual industrial installations. Its principal effect would be to preserve a larger buffer that could become available if future market conditions trigger the release mechanism.

      For manufacturers planning investments extending into the 2030s, the availability of allowances and the future trajectory of carbon prices influence production costs and the commercial case for decarbonisation technologies.

      Carbon market figures reveal changing conditions

      The European Commission reported in May that the total number of allowances in circulation during 2025 stood at approximately 1.023 billion.

      Its annual market stability reserve calculation provided for approximately 190.5 million allowances to be withdrawn from auctions between September 2026 and August 2027.

      These withdrawals reflect the existing mechanism for reducing market surpluses. The proposed higher invalidation threshold concerns how many allowances can subsequently remain in reserve rather than being cancelled.

      The overall emissions cap will continue to decline under the legislation already governing the ETS.

      Consequently, preserving a larger reserve does not remove the long-term constraint on emissions or guarantee lower carbon prices for European industry.

      The agreement also concerns the established ETS covering power generation, industry and certain other sectors, rather than the separate ETS2 regime for emissions associated with road transport and buildings.

      The latter has generated its own political controversy, as EU Today reported following the October European Council summit.

      Broader ETS reform remains unresolved

      The Council and Parliament have agreed that the question of gradually reducing the invalidation threshold should be considered during the broader ETS review.

      That exercise will address the carbon market’s operation over a longer period, when the declining supply of allowances could create tighter conditions.

      The present agreement therefore provides an adjustment to the reserve mechanism without reopening the entire emissions trading framework. Following legal and technical finalisation, the provisional deal must be endorsed by both institutions and formally adopted.

      The new 700 million threshold would apply after the legislation takes effect, while the larger review of the ETS continues through the EU legislative process.

      •  
      ❌