❌

Reading view

Trump's 50% Tariffs on Canadian Goods Illegally Rely on a Superseded Statute, a Lawsuit Argues

a shipping container and a maple leaf with President Donald Trump in the background | Molly Riley/B66/Avalon/Newscom/Skypixel/Dreamstime

Last July, President Donald Trump imposed 50 percent tariffs on various Canadian goods, a list he subsequently expanded to include additional imports, some of which he banned outright. His legal justification was Section 338 of the Smoot-Hawley Tariff Act, which Congress approved in 1930. Section 338 authorized tariffs in response to discriminatory trade practices. But in the 96 years since it was enacted, no president had ever used it to impose tariffs.

Why is that? According to a lawsuit that the Liberty Justice Center (LJC) filed on Tuesday in the U.S. Court of International Trade (CIT), the answer is clear: Section 338 was superseded by subsequent legislation that likewise targeted discriminatory trade barriers, beginning with the Reciprocal Trade Agreements Act of 1934 and culminating in Section 301 of the Trade Act of 1974. Section 301, the current remedy, includes requirements that Trump apparently sought to dodge by invoking Section 338 instead.

That maneuver is illegal, the LJC argues. "Congress already gave the executive branch a tool for responding to unfair foreign trade practices: Section 301, which requires an investigation, public comment and other safeguards," says Jeffrey M. Schwab, the LJC's director of litigation. "The administration cannot skip those protections by reaching for a 1930 statute that no president had ever used to impose a tariff."

Why not? "Where provisions in two acts are in irreconcilable conflict, the later act, to the extent of the conflict, constitutes an implied repeal of the earlier one," the lawsuit says. "Where a later act covers the whole subject of an earlier one and is clearly intended as a substitute, it operates similarly as a repeal. And a specific policy embodied in a later federal statute controls the construction of an earlier one even absent express amendment."

Even if Section 338 somehow survived congressional approval of contrary laws, the LJC adds, Trump's tariffs exceed the authority it grants. And if Trump's interpretation of Section 338 were correct, the lawsuit says, the provision would violate the nondelegation doctrine, which bars Congress from delegating its tariff power to the president without providing "an intelligible principle" to guide and constrain his exercise of it.

Trump's Section 338 tariffs, in short, are "the Administration's latest attempt to exercise, through a statute never designed for the purpose, the tariff power that the Constitution assigns to Congress." That pattern should be familiar by now.

Shortly after taking office in 2025, Trump claimed to have discovered a previously unnoticed delegation of extensive tariff authority in the International Emergency Economic Powers Act (IEEPA), a 1977 law that does not mention import taxes and had never been used to impose them. That claim was rejected by every court that considered it, and last February the Supreme Court ruled that IEEPA does not authorize tariffs at all.

Trump responded to that decision by immediately announcing similarly broad tariffs under Section 122 of the 1974 Trade Act, which addresses "fundamental international payments problems" caused by "serious United States balance-of-payments deficits." In May, the CIT ruled that the new tariffs were illegal because Trump had failed to "identify balance-of-payments deficits within the meaning of Section 122."

Trump then switched to Plan C, invoking Section 301 of the Trade Act, which authorizes tariffs in response to a foreign "act, policy, or practice" that is "unreasonable or discriminatory" and "burdens or restricts" U.S. commerce. He claimed that provision justified tariffs on 86 trading partners, accounting for nearly all U.S. imports, because they had failed to "impose and effectively enforce a prohibition on the importation of goods produced with forced labor." The CIT is currently weighing challenges to those tariffs, including an LJC lawsuit.

Trump's Section 338 tariffs have now added to the CIT's caseload. The LJC represents Gellert Global Group, an importer that was hit hard by those taxes after Trump added cheese to the list of disfavored Canadian goods. The lawsuit asks the CIT to certify a class of importers, numbering in "the hundreds, if not the thousands," that likewise have been clobbered by Trump's 50 percent tariffs.

Since Trump obviously is aware of Section 301, why did he resort to a never-used, seemingly obsolete provision to justify the tariffs on imports from Canada? As the LJC notes, Section 301 requires an investigation by the Office of the U.S. Trade Representative, "consultation with the foreign country concerned, notice, public comment, a hearing, and determinations within statutory deadlines." It also requires "that action be equivalent in value to the burden imposed, that duties be preferred over other import restrictions, and that actions terminate after four years absent a request for continuation and review."

Can Trump avoid those constraints by invoking Section 338 instead? The LJC thinks not: "Congress did not intend to leave in place a parallel authority that would allow the President to impose the same remedies, for the same conduct, free of every one of those safeguards."

Section 338 has been "impliedly repealed," the LJC argues. "At a minimum, Section 301 controls where, as here, the President seeks to respond to foreign practices within Section 301's scope, and the President may not impose duties in response to such practices while disregarding the procedures and limits Section 301 imposes. Because the President did not proceed under Section 301, the Section 338 Tariffs are unlawful whether or not Section 338 survives."

Even if you ignore subsequent legislation, the LJC argues, the Canadian policies that Trump cited when he announced the tariffs do not qualify as "discrimination" under Section 338. "Canada's motor vehicle surtax and its provinces' alcohol purchasing decisions are responses to tariffs that the United States imposed on Canada, not discrimination by Canada against the United States," it says. Trump also complained that Canada treats European cheese imports more favorably than U.S. cheese imports. But "when Congress enacted Section 338, a preference granted under a reciprocal agreement was not 'discrimination.'"

Section 338 "addresses discrimination: measures that single out United States commerce for worse treatment than the commerce of the world at large," the lawsuit says. "It is not a general authorization to impose tariffs whenever the President disagrees with a trading partner's policies, or whenever a trading partner responds to tariffs the United States has imposed on it."

Trump also was unfazed by Section 338's requirement that the president set duties to "offset" the costs imposed by discriminatory practices, which implies proportionality. Rather than attempt that, the LJC notes, Trump imposed "the statutory maximum rate of 50 percent without tying it to any measured burden."

As interpreted by Trump, the lawsuit warns, Section 338 authorizes the president to "impose tariffs of up to 50 percent on any products of any country that extends better treatment to any other country in any respect—including through any of the hundreds of preferential trade agreements to which the United States is not a party—or that responds to tariffs the United States has imposed on it." Yet Section 338 "contains no clear statement authorizing that power," contrary to the "major questions" doctrine, which applies to assertions of executive authority with "vast economic and political significance."

If Section 338 conferred the sort of unfettered authority that Trump is claiming, the LJC says, it "would supply no intelligible principle constraining the exercise of Congress's power to lay duties." His reading "would convert a narrow, fact-dependent provision into an effectively unrestricted delegation of Congress's tariff power," which would be "an unconstitutional delegation of legislative power."

This case "is not about the president," says LJC CEO Sara Albrecht. "It is about the presidency. No president should have the power to pull a dormant statute off the shelf and use it to impose sweeping tariffs or import bans without the limits Congress required."

The post Trump's 50% Tariffs on Canadian Goods Illegally Rely on a Superseded Statute, a Lawsuit Argues appeared first on Reason Magazine.

  •  

Trump's $8 Billion Diesel Bailout Pays Farmers for a Problem He Created

TrumpFarm | Andrew Leyden/ZUMAPRESS/Newscom/Donland/Dreamstime

On Monday, the U.S. Department of Agriculture (USDA) announced it would "make $8 billion available for one-time payments to American farmers this harvest season to provide relief during temporary market disruptions and increased input costs."

Using a formula derived from the USDA's production, yield, and price estimates, the Harvest Fuel Relief program will "provide simple, proportional support to producers." It will only cover a "portion of modeled losses during the 2026 crop year." The Farm Service Agency—an office within the USDA that administers credit and loan programs—will administer the $8 billion in one-time payments using funds from the Commodity Credit Corporation, a federal entity authorized to draw up to $30 billion from the U.S. Treasury to fund agricultural initiatives. Payment rates won't be released until November, and the USDA's notice leaves open the possibility of additional payments for "non-Title I commodities, including specialty crop growers and fishermen."

A fiscally questionable decision, the program comes at a time when farmers are feeling a significant price pinch. The dyed diesel American farmers and ranchers use is exempt from state and federal highway taxes, but that has done little to offset skyrocketing fuel prices. In September, the American Farm Bureau Federation projected that fuel expenses would reach $22 billion this year, up 29 percent from 2025. The Farm Bureau estimates that total production expenses will reach nearly $500 billion in 2026. According to its own predictions, the USDA doesn't expect the situation to improve anytime soon.

In its latest Commodity Costs and Returns report, released in June, the USDA projects farmers and ranchers will face record production costs in 2027—higher than during the COVID-19 supply chain disruptions—driven by higher prices for necessary inputs such as fuel, fertilizer, seeds, machinery, and labor. 

While the USDA has blamed "temporary market disruptions" for these cost hikes, the blame more accurately falls to President Donald Trump, thanks to his illegal war in Iran. As of Tuesday, Trump's war—and the subsequent shocks it has caused to the global diesel supply—have pushed the national average price in the U.S. up $2.70 per gallon from a year ago, a 74.6 percent increase, according to AAA data.

Unfortunately, the war in Iran is just one of several Trump administration policies making life more expensive for everyone, including the nation's farmers and ranchers. Tariffs on imported fertilizer, which began in 2020 during the first Trump administration, have made it difficult for American farmers to afford what they need. By the Farm Bureau's estimates, fertilizer costs for 2026 are projected to reach a record $40 billion, up 15 percent from the previous year.

The $8 billion program is part of a windfall of taxpayer money the Trump administration has sent to farmers as relief for harms caused by the president's actions. Last December, the USDA sent $11 billion in one-time bridge payments to more than half a million farmers nationwide. Earlier this month, the USDA announced it would provide a record $13.8 billion in gross payments to agricultural producers to cover revenue losses. 

In a speech in Kansas touting the program, Trump claimed that the state's residents would see a "plunge" in prices once the war ends. That's likely an exaggeration, given the host of questionable economic policies he seems hell-bent on implementing. 

Still, that shouldn't discredit the president's suggestion. Ending the war would benefit farmers, ranchers, and consumers, without doling out billions in another government bailout for a favored industry.

The post Trump's $8 Billion Diesel Bailout Pays Farmers for a Problem He Created appeared first on Reason Magazine.

  •  

Liberty Justice Center Files First Lawsuit Challenging Trump's Section 338 Tariffs Against Canadian Imports

An American flag breaks with a Canadian flag
Illustration: Midjourney

Today, the Liberty Justice Center (LJC) filed Gellert Global Group Corp. v. Trump, the first lawsuit challenging President Donald Trump's massive Section 338 tariffs against a variety of Canadian imports. The case was filed in the US Court of International Trade (which has jurisdiction over tariff-related cases); Gellert Global Group is an importer of Canadian cheese subject to the tariffs. LJC is the same public interest group that I worked with on the case challenging Trump's earlier IEEPA tariffs, which ultimate resulted in their invalidation by the Supreme Court. I am not directly involved in the present case. But I support it and believe it deserves to prevail.

LJC has also filed cases challenging Trump's massive Section 122 and Section 301 tariffs. They have become America's premier public interest law group standing up for free trade and enforcing constitutional constraints on executive power over trade restrictions.

Section 338 was part of the infamous Smoot-Hawley tariff act of 1930, which gravely exacerbated the Great Depression. It has never been used before, likely because it was superseded by later laws.

I have previously written about why Trump's Section 338 tariffs are harmful and illegal. See my recent Montreal Economic Institute paper on this topic, and earlier pieces here, here, and here. To briefly summarize, the tariffs on Canada are illegal because 1) Section 338 has been superseded by later legislation, 2) even if Section 338 is still operative, Trump's tariffs do not meet its requirements because the Canadian actions they supposedly respond to do not "discriminate" against US goods, as the law requires, 3) Trump's tariffs do not "offset" the Canadian actions (as Section 338 also requires), but go far beyond that, 4) the administration's interpretation of Section 338 runs afoul of the "major questions" doctrine, and 5) if Section 338 is operative and does authorize the Trump actions, it would violate the constitutional nondelegation doctrine (which restricts delegation of legislative power to the executive).

The LJC complaint advances all five of these arguments. To prevail, they need win on only one. They also add a few more technical points that I will not try to cover here. LJC further seeks a class action certification for a class of all those importers subject to the Section 338 tariffs. If this succeeds, it would block all enforcement of Section 338 tariffs, not just those paid by Gellert.

This lawsuit does not directly challenge Trump's extension of the Section 338 action to categorically ban some Canadian imports, in addition to imposing tariffs. As far as I can tell, Gellert does not import goods subject to the ban (as opposed to the tariffs). However, as I explained here and here, the legality of the bans is dependent on that of the initial tariffs. In a recent Lawfare article, I outline the reasons why executive-imposed import bans are subject to most of the same legal constraints as executive-imposed tariffs.

Like the IEEPA, Section 122, and Section 301 tariffs, Trump's use of Section 338 is an attempt to convert a limited delegation of authority into a blank check enabling the president to impose tariffs whenever he wants. Courts should reject all of these power grabs.

I commend LJC for bringing this important case. And I hope and expect it may not be the last lawsuit challenging the Section 338 measures. Future cases might well challenge the import bans directly, as well as the tariffs.

The post Liberty Justice Center Files First Lawsuit Challenging Trump's Section 338 Tariffs Against Canadian Imports appeared first on Reason Magazine.

  •  

You Can Trade Contracts on Elections, but Not on Onions. These College Students Want To Fix That.

Student protestors | Photo: For Our Futures/X

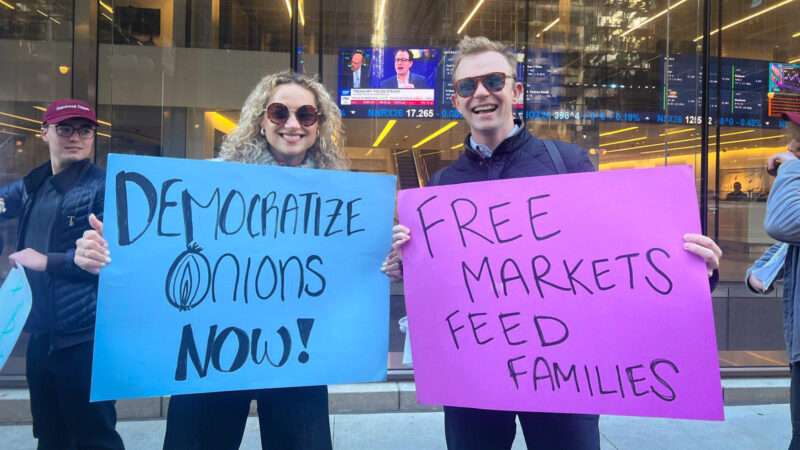
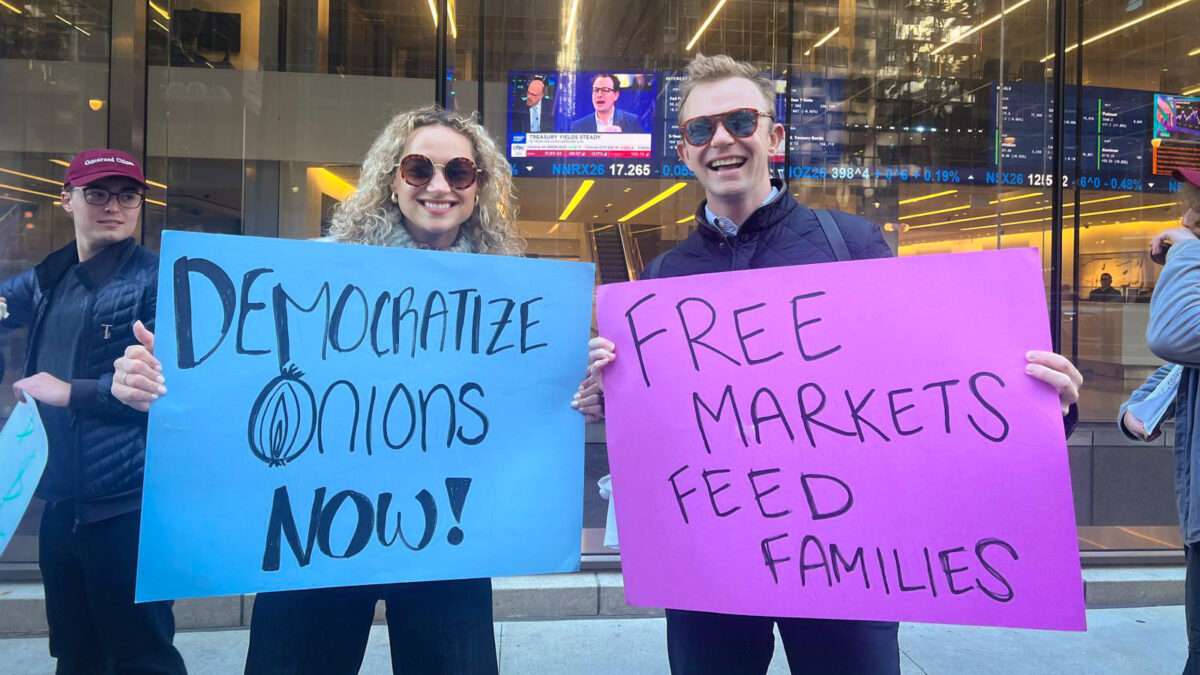
On Monday, a group of students from the University of Chicago stood outside the Chicago Mercantile Exchange—one of the world's largest and most diverse derivatives marketplaces—and called for the repeal of an obscure 1958 law that bans onions as futures products traded on U.S. exchanges. 

Attracting an audience with a humorous jingle and amusing signs that included "Onions Deserve a Future," "Honk If You Want Free Onions," "Hot Girls Hedge Onions," and "Free Markets Feed Families," the student group, named For Our Futures, has a simple platform: a repeal of the 1958 Onion Futures Act, which prohibits anyone from trading in onion futures on commodity exchanges. (The law was amended in 2010 to ban motion picture box office receipts from being traded on commodity exchanges.) The viral campaign drew enough attention that Mike Selig—chairman of the Commodity Futures Trading Commission and a proponent of expanding the list of commodities traded on futures markets—was asked about the law in a media appearance. 

American farmers produce about 6.75 billion pounds of onions a year, according to the National Onion Association, an industry trade group. While peers who grow cotton, wheat, corn, and soybeans can hedge against price swings by trading futures contracts, onion farmers have no such recourse under federal law. But, as the Agriculture Department's daily National Potato and Onion Report shows, onion prices are highly volatile and subject to wild swings, making them an ideal market for futures trading. 

In its latest report, released Monday, the agency shows that onion prices have roughly doubled since this time last year. If onion futures contracts were legal, farmers could rely on market expectations instead of planting crops based on last year's prices. It would also let buyers potentially cut costs by locking in lower prices to protect against spikes. Trading onion futures contracts would give the industry a useful price-discovery tool, one that the student group aptly notes is "crucial for price stability and for hedging risks associated with weather and market fluctuations."

It's not For Our Futures' first time trying this gambit. The student group staged similar protests at college campuses in April and May, armed with bags of raw onions to entice passersby into signing their petition to legalize onion futures. The students' crusade might be comical, but after a recent Gallup poll found that 57 percent of Americans age 18–34 have a positive image of socialism, it's encouraging to see college-age students stand up for free markets.

A protest over onions sounds absurd, but it's a viral reminder to others in that age cohort of how far governments can go when given the slightest leeway to regulate an industry.

Instead of relying on outdated price points when planning future harvests, American onion producers could use resources like futures contracts that offer real-time market signals. All that would require—as the college kids state—is for federal lawmakers to "let the free market reign supreme."

The post You Can Trade Contracts on Elections, but Not on Onions. These College Students Want To Fix That. appeared first on Reason Magazine.

  •  

EU Signs Association Agreements with Andorra and San Marino, Opening Single Market Access

The European Union has signed a comprehensive association agreement with Andorra and San Marino, establishing a framework that will allow the two small European states to participate more fully in the EU single market while remaining outside the bloc.

The agreement was signed in Brussels on Monday, 19 October, by representatives of the European Commission and the two governments, marking the conclusion of negotiations that began more than a decade ago.

The arrangement covers trade, investment and regulatory cooperation, alongside provisions concerning financial services, education, environmental protection, consumer rights and other areas normally governed by EU legislation.

However, the agreement has not yet entered into force. It requires further approval procedures, including consent from the European Parliament and ratification by the participating countries. Andorra intends to submit the agreement to a binding national referendum.

Access to the European single market

According to the European Commission’s announcement, the agreement will provide Andorra and San Marino with access to the single market under shared regulatory requirements and conditions intended to ensure fair competition.

The principal objective is to remove barriers that continue to restrict economic activity between the two countries and the EU’s 27 member states.

For businesses, the arrangements should provide greater predictability concerning the rules governing cross-border trade, investment and commercial operations.

Participation will nevertheless require both countries to implement relevant EU legislation and maintain systems capable of enforcing the applicable standards.

In practice, access to the European market will carry obligations comparable to those imposed on companies established inside the Union, particularly concerning product standards, competition, environmental rules and consumer protection.

The agreement also establishes institutional arrangements for managing cooperation and dealing with future regulatory developments.

For two countries whose economies are closely connected to neighbouring EU members, greater regulatory consistency could reduce administrative barriers and facilitate commercial expansion.

Financial services to be integrated gradually

Financial services represent one of the more sensitive elements of the agreement.

Andorra has a banking and financial sector with substantial links to Spain and France, while San Marino’s economy is closely integrated with Italy.

Both countries already use the euro under separate monetary arrangements with the European Union, although neither is a member of the eurozone or the EU.

The new association framework would provide a route towards broader participation in the EU financial services market, but integration will be gradual and subject to specific conditions.

The Commission has made clear that the process will involve assessments of the regulatory and supervisory arrangements operating in both countries.

This means the signature does not provide their financial institutions with immediate, unrestricted access to all services available within the EU.

Brussels has also signed updated monetary agreements designed to remove overlapping requirements between existing arrangements and the new association framework.

Financial supervision, the prevention of money laundering and compliance with European regulatory standards will be central to the implementation process.

Integration without EU membership

The agreement illustrates how the Union can extend significant elements of its economic framework to neighbouring countries without admitting them as members.

Andorra and San Marino will not acquire voting rights in EU institutions or the political representation enjoyed by member states.

Their participation will instead depend on accepting relevant common rules and complying with the institutional provisions established under the association agreement.

The EU already operates differentiated arrangements with several non-member European countries, including Norway, Iceland and Liechtenstein through the European Economic Area.

Earlier European Council conclusions on relations with non-EU Western European countries identified Andorra and San Marino among the states with which Brussels sought closer economic and institutional cooperation.

The newly signed agreement does not replicate every aspect of existing arrangements, but it follows the broader principle that access to the single market can be negotiated separately from EU membership.

That principle is also relevant to discussions about how candidate countries might receive selected economic benefits before completing the full accession process.

Brussels has been considering wider market participation for countries such as Ukraine and Moldova ahead of possible membership.

Referendum and ratification ahead

The immediate political challenge now moves from negotiation to approval.

Following the signature, the Council will seek the European Parliament’s consent before the agreement can be formally concluded. Its application will also depend on the completion of the necessary national procedures.

In Andorra, Prime Minister Xavier Espot’s government has committed to a binding referendum, although no voting date has yet been fixed.

The referendum will determine whether Andorran voters accept the economic opportunities and regulatory commitments established by the agreement.

San Marino must also complete the procedures required under its constitutional system.

Until those requirements have been satisfied, the agreement remains a signed framework rather than an operational extension of the EU single market.

For both countries, the eventual implementation will determine how far their economies can integrate with the Union while retaining their existing status as independent non-member states.

  •  

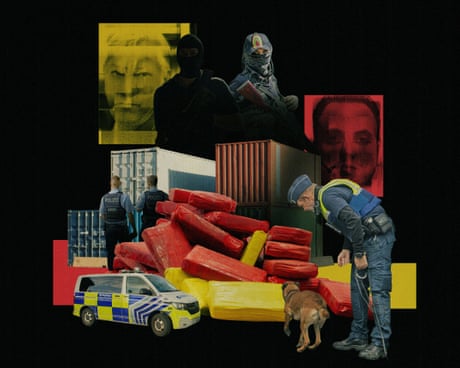
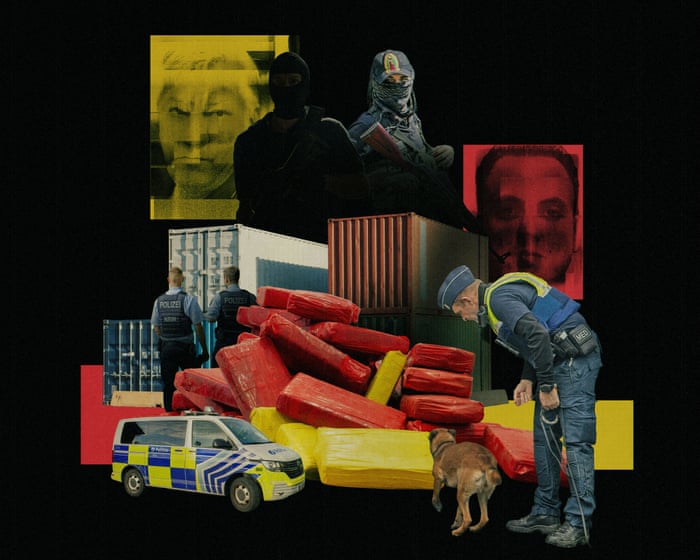
The ‘Finger cutter’ and the ‘Brazilian Escobar’: the men accused of bringing cocaine cartels to Europe

A Belgian criminal organisation’s links with a Brazilian cocaine gang have been the focus of a major trial in Brussels, where smuggling links have been alleged between European players and the drug cartels of Latin America

In the early hours of 7 September, a convoy of heavily armed police swept through the sleeping streets of central Brussels towards the Haren district, on the city’s north-eastern outskirts. They made their way to 22 Avenue du Bourget, a militarised bunker-like complex that was the former headquarters of Nato.

The modernist complex, with its austere and functional architecture, was hastily built in 1967 and houses the Justitia courtroom, where Belgium’s federal trials are now held. It was here that the perpetrators and accomplices of the 2015 Paris terrorist attacks and the 2016 Brussels attacks were tried in 2022.

Continue reading...

© Composite: Guardian Design/Belga/AFP/Getty Images/AP/Europol

© Composite: Guardian Design/Belga/AFP/Getty Images/AP/Europol

© Composite: Guardian Design/Belga/AFP/Getty Images/AP/Europol

  •  

‘Narcos have one language – violence’: the activist defying France’s biggest drug cartel after his brothers’ murder

Amine Kessaci, 23, lives under constant threat as trial of five men becomes focus of nation’s battle with mafia-style crime

At 23, he is one of the most heavily protected people in France, constantly sleeping in different locations to escape the threat of contract killers from the country’s biggest drug cartel.

“Narcos and drug traffickers only have one language, one method: violence,” said Amine Kessaci, a young law student from a Marseille housing estate, who, after the murders of his two brothers, has become the most outspoken voice against the Latin American-style narco gangs expanding their reach across France.

Continue reading...

© Photograph: Thibaud Moritz/AFP/Getty Images

© Photograph: Thibaud Moritz/AFP/Getty Images

© Photograph: Thibaud Moritz/AFP/Getty Images

  •  

Trump's War With Iran Pushed Him To Waive a Century-Old Shipping Law. Commerce Boomed.

A large boat with shipping containers seen from above | Tawatchai Prakobkit/Dreamstime/Cato Institute

America's interminable war with Iran has killed thousands, disrupted commerce that flows through the Strait of Hormuz, and raised prices on the home front.

But there may be one silver lining. In an attempt to lower gas prices that spiked because of the war, the Trump administration has repeatedly issued waivers of the Jones Act, a century-old law that requires all goods moved between American ports to be carried on American-built, American-crewed ships.

With the law (temporarily) not being enforced, commerce has exploded.

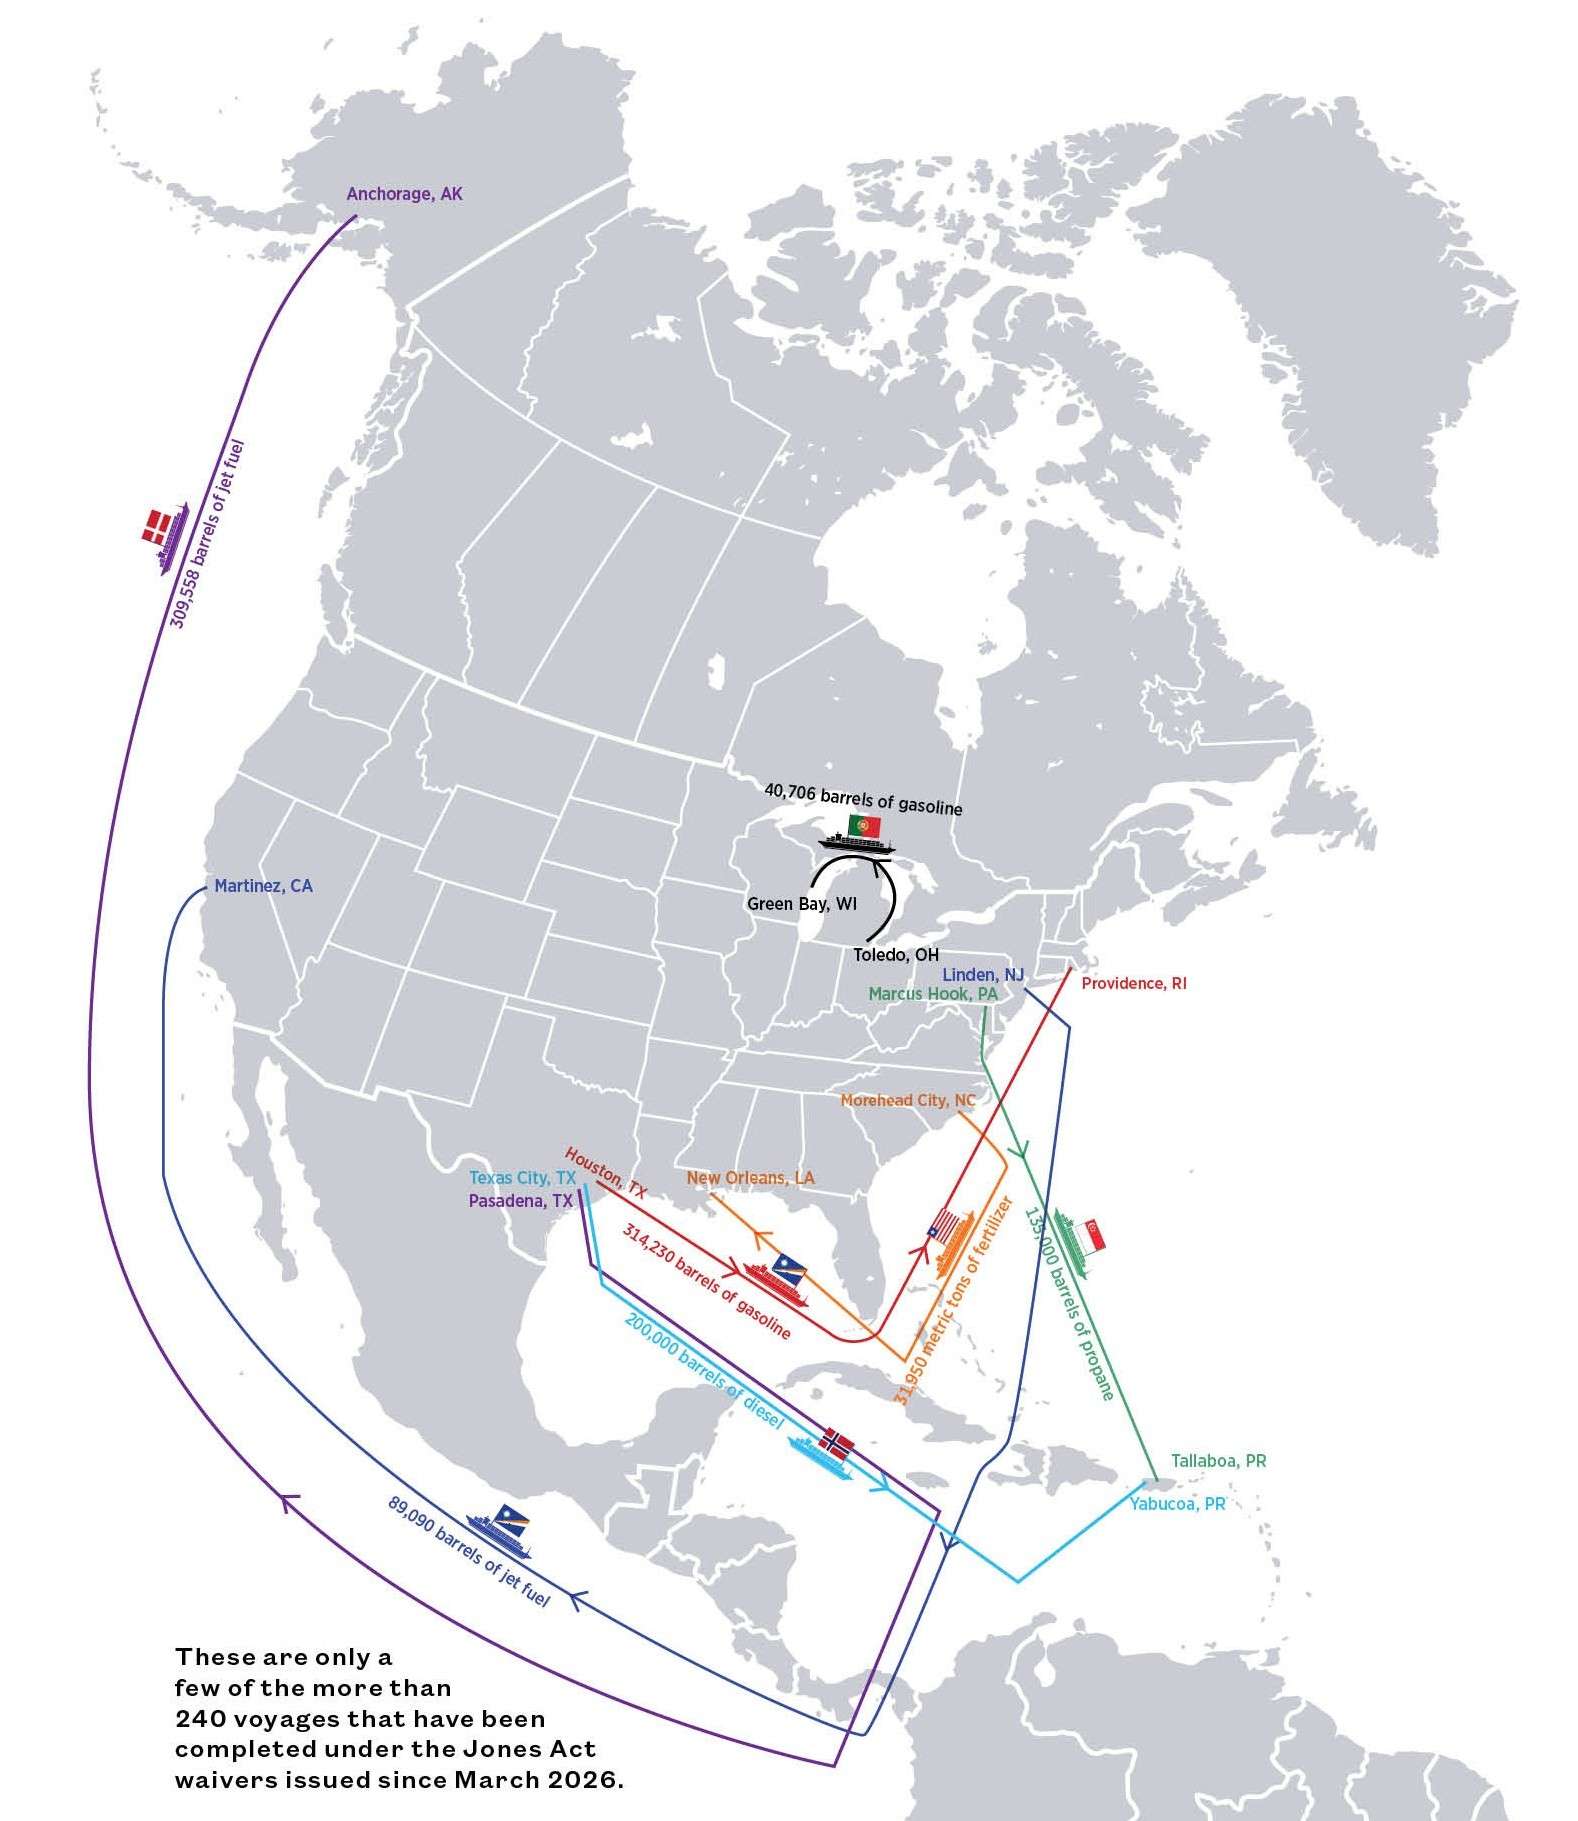
Just look at how much propane has been shipped from the mainland United States to Puerto Rico, says Colin Grabow, a trade policy analyst at the Cato Institute and perhaps the nation's foremost advocate for abolishing the Jones Act.

A map showing U.S. fuel shipping routes
Cato Institute / Joanna Andreasson

Since March, when the first waiver was issued, Puerto Rico has imported more than 800,000 barrels of propane from the mainland. That's more than twice the amount of American propane shipped to Puerto Rico in the last 22 years combined.

America is one of the world's leading producers and exporters of propane, but the lack of Jones Act–compliant ships capable of carrying gas means that it has been nearly impossible to ship propane from the mainland to outlying parts of the country. In the past, Puerto Rico has imported gas from Nigeria, Chile, and elsewhere because those deliveries don't have to comply with the Jones Act.

For years, libertarians have argued that the Jones Act unfairly impoverishes American consumers and businesses that want to buy and sell things within the same country in order to artificially inflate the price of moving those things across water. Waiving the law seems to have proven that point: There are plenty of ships capable of moving gas and oil around the country as long as the government gets out of the way.

"The instant the Jones Act no longer applied to energy shipments, mainland propane displaced foreign imports, suggesting it had been the cheapest option all along," says Grabow.

Puerto Rico is hardly the only winner.

The Jones Act waivers are offering a glimpse into a world where the law doesn't exist. From March through mid-August, there had been 210 voyages completed that otherwise would have been deemed unlawful without the waivers, according to an analysis of Maritime Administration data by the Institute for Energy Research.

It's a world where American oil and natural gas can be more easily shipped from the Gulf Coast to New England, which had previously been importing energy from Russia and Europe. Another big winner is California, which had been importing gasoline from as far away as the Bahamas because it was nearly impossible to legally ship gas from Texas or Alaska to the West Coast.

President Donald Trump reupped the Jones Act waiver in mid-May. Another extension, issued in August, will last for 90 days but applies only to ships carrying energy products such as gas and oil. Before that waiver expires in November, lawmakers ought to kill the Jones Act permanently.

There is some irony in the fact that one of Trump's most successful policy maneuvers has paused a protectionist law that limited commerce, when so much else of his economic policy has been focused on erecting barriers to trade. It's also amusing that it was a war in the Middle East—something Trump pledged to avoid—that triggered this change.

Still, the proof is in the shipping. The free traders were right all along.

The post Trump's War With Iran Pushed Him To Waive a Century-Old Shipping Law. Commerce Boomed. appeared first on Reason Magazine.

  •  

The resilience of the world economy is built on illusion – it’s time the West woke up

By Marco CARNELOS

Join us on Telegram, X, and VK.

Contact us: info@strategic-culture.su

Record debt, a paralysed trade-dispute architecture and the normalisation of sovereign-asset seizure as a policy tool means fragility is baked into the global economic system

Since 2022,  a steady drumbeat of forecasts has warned that cascading military and political upheavals – war in Ukraine, conflict in the Middle East, an accelerating tariff war, the weaponisation of sanctions and the disruption of energy supplies – would eventually overwhelm the world economy’s capacity to absorb shocks.

The most destructive of those scenarios have not materialised, or at least not yet.

As the IMF’s managing director Kristalina Georgieva stated last year, while previewing the fund’s World Economic Outlook, the global economy “has generally withstood significant strains from various shocks”.

Although that resilience is real, on closer inspection, it is a more fragile and more contested achievement than it first appears.

The adaptive mechanisms behind this resilience are visible and measurable. Trade has rerouted rather than collapsed. Energy corridors have diversified. And reserve managers have spent the past three years quietly re-engineering the architecture of the international monetary system.

According to the World Gold Council’s 2026 Central Bank Gold Reserves survey – which drew responses from 76 institutions, its highest participation in nine years – 89 percent of central banks expect global gold holdings to keep rising over the next year, with a record share planning to add to their own reserves.

The result: gold has overtaken US Treasuries as the largest single component of global central bank reserves for the first time since the mid-1990s.

Mother of all ticking bombs

Analysts tracking the shift link it directly to a single event: reserve managers were unsettled by the seizure of the Central Bank of Russia’s reserves at the start of the Ukraine war by Washington and have since been actively reducing the dollar share of their portfolios.

This is a clear example that the economic system is not breaking under political pressure, it is adapting to it – flexibly, and crucially, without severing the interconnections that make global trade and finance function at all.

In other words, central banks accumulating gold are not exiting the system; they are just hedging within it.

But adaptability has a cost, and that cost is compounding.

Global debt – government, household, corporate and financial combined – surpassed $365 trillion in the first half of 2026, according to the Institute of International Finance’s Global Debt Monitor, the sixth consecutive quarterly record.

Emerging-market debt alone rose by $6.5 trillion in the same period, breaking past $110 trillion. Georgieva has been blunt about the trajectory: speaking at the IMF and World Bank annual meetings, she warned that global public debt is projected to reach 110 percent of the world’s GDP by 2029.

There is an evident reluctance to address what is not a crisis in any single country’s balance sheet, but a structural drift that every major economy appears aware of and none is prepared to correct unilaterally.

Debt of this scale narrows the fiscal space available to absorb the next shock, military or otherwise, which is precisely what makes today’s resilience difficult to extrapolate into tomorrow’s.

In this context, there is also the mother of all ticking bombs, a nuclear one: the $40 trillion US federal debt which US Secretary of Treasury Scott Bessent is desperately trying to reign in.

The third strand, the onslaught of punitive political measures targeting market principles, is best illustrated by the fate of Russia’s frozen central bank reserves. Roughly $300bn in Russian sovereign assets have been immobilised globally since 2022, with some €210bn ($235bn) held within the European Union.

Erosion of neutrality

Rather than remaining in legal limbo, these reserves have become the financial engine of a specific policy outcome: the EU’s proposed €140bn ($157bn) “reparations loan” to Ukraine, structured so that Ukraine would repay it only once Russia itself pays war damages – effectively converting a sanctions freeze into a grant.

Russia’s central bank has responded by suing the Brussels-based depository Euroclear, which holds the bulk of the assets, calling the manoeuvre illegal.

Whatever one’s view of the underlying conflict, the precedent is the point economists increasingly raise: the first large-scale use of frozen sovereign reserves as collateral for a geopolitical objective changes the calculus for every reserve-holding state watching from outside the western bloc.

It is one more data pointing to the reinforcing of the gold-accumulation trend described above – and a vivid example of how political tools aimed at a single adversary can erode the perceived neutrality of the system itself.

A parallel erosion is under way in trade governance. The WTO’s Appellate Body (the one supposed to settle trade dispute among countries) has been non-functional since December 2019, after the United States blocked the appointment of new judges and talks on reviving or replacing it remain stuck.

More than 30 appeals currently sit unresolved, and the workaround mechanism created to fill the gap – the Multi-Party Interim Appeal Arbitration Arrangement – has resolved only a single case. The institution designed to prevent trade disputes from becoming purely a function of relative power has been quietly sidelined for seven years.

It is then worth wondering – in such a situation – if the Global West and Global Rest see the same picture here.

The evidence suggests convergence on diagnosis but real divergence on meaning. Both recognise that debt is unsustainable and that institutions are strained. But where western policymakers tend to treat sanctions, frozen assets and trade paralysis as defensive responses to external aggression.

Voices from the Global Rest increasingly read the same tools as confirmation that the system was never as neutral as advertised.

India’s External Affairs Minister S Jaishankar captured this gap memorably in 2022, telling European interlocutors that Europe needed to “grow out of the mindset” that its problems are everyone’s problems while the reverse does not hold.

Selective status

This is something many Global Rest governments had been thinking but not saying aloud: that the postwar order’s claim to universality was always, in practice, more selective than it appeared.

The more honest and outspoken western leader to recognise such an unfair situation, to use an understatement, was Canadian Prime Minister Mark Carney earlier this year in Davos.

None of this means the system is about to fracture. The world economy has proven more elastic than feared, absorbing shocks that a decade ago might have triggered genuine crisis. But elasticity and durability are not the same thing.

The real test of this sort of “economy of resistance” is not whether it survives the next military-political storm – it plainly has, repeatedly.

It is whether record debt, a paralysed trade-dispute architecture, and the normalisation of sovereign-asset seizures as a policy tool are quietly converting what is in effect a short-term adaptability into long-term fragility, especially at a moment when the Global Rest and Global West can no longer agree on what the system is actually for.

Original article:  www.middleeasteye.net

  •  

EU ‘open’ to curbs on imports of Chinese chemicals and machinery, after hybrid-car deal

The EU is preparing to curb Chinese imports of chemicals and industrial machinery, following a successful deal with Beijing that capped hybrid car exports to the bloc.

The European Commission “showed openness” to proposing safeguards, referring to an emergency brake on imports that can cover entire sectors, an EU diplomat told EUobserver on Thursday (15 October).

And there was “broad support” for the idea among member states for the commission to proceed, the diplomat said.

Last week, trade commissioner Maroš Šefčovič agreed with Beijing to cap imports of Chinese hybrid cars at 350,000 next year, which was less than half the amount expected this year.

He called the deal a “blueprint” for other sectors, a view which was publicly echoed by EU Commission president Ursula von der Leyen, also on Thursday. 

Under World Trade Organization (WTO) and EU rules, anti-dumping and anti-subsidy cases require Brussels to prove that Chinese firms sell at unfairly low prices or receive subsidies.

Safeguards do not need evidence under WTO rules, which allows them to be used as an emergency measure.

And the commission only has to show that a surge in imports is seriously harming European producers. 

“We like the idea, chemicals, machinery where there’s still a lot of Chinese overproduction needs to be managed,” said another EU diplomat.

The instrument had its limits: Safeguards have to apply to all countries, not just China, and can last no more than eight years.

The EU rarely uses WTO safeguards, but did so on steel, also aimed at China, which expired in June, after reaching the eight-year limit, and which have since been replaced by a separate EU steel regime.

And the Centre for European Reform, a prominent think-tank in Brussels, previously suggested exempting the EU’s 76 free-trade partners from safeguards so that the measures fell mainly on China.

It was a legal moot point in the WTO if that was OK, but the EU has done something similar before. 

Norway, Iceland, Liechtenstein, and 10 other countries were left out of the steel safeguard, but using this tool to address Chinese imports was still seen as a temporary solution.

Before the end of the year, the EU commission aims to present diversification tools to reduce reliance on Chinese goods, as well as a mechanism to compensate companies hit by Chinese countermeasures.

And the package would include an instrument to shut Chinese companies out of the EU market if need be, in a measure first proposed in a Franco-German paper last week.

  •  

EU leaders uniting on tougher China trade defence, but clash over carbon pricing rules

Europe’s trade deficit with China reached a record $34.8bn [€31bn] in September, as EU leaders meet in Brussels on Thursday (15 October) to discuss Europe’s competitiveness agenda and what they call “macroeconomic imbalances” — a euphemism to avoid mentioning China by name.

EU heads of state and government are expected to give a mandate to the EU Commission to propose a set of trade defence measures and tools to reduce the EU’s reliance on Chinese industry, based on a new Franco-German blueprint, as a united front spreads across the bloc. 

There was a move towards a “surprising unitary position” on Beijing among member states, said an EU diplomat, ahead of a two-day summit in Brussels which began on Thursday (15 October).

A joint letter and policy paper submitted by French president Emmanuel Macron and German chancellor Friedrich Merz to commission president Ursula von der Leyen last week was viewed by many EU diplomats as marking a decisive shift towards a more consolidated EU stance on trade relations with China. 

“For a long time, there were significant differences between these two countries on how to deal with China, how to address the economic situation,” parliament president Roberta Metsola told reporters on Thursday. 

The diplomat added that the commission’s trade diversification package, designed to reduce the bloc’s reliance on Chinese industrial inputs and curb Chinese exports, will be presented by the end of the year and will be based on the Franco-German paper. 

But the commission, for its part, has downplayed the prospect of rapid progress to EU-Chinese trade statistics. “It’s an issue which is not going to be solved in a couple of months,” said one official. 

‘Be ready for escalation’ but do nothing

This article continues, but the full version is available only to EUobserver.com subscribers. Visit account.euobserver.com/membership

  •  

EU and Turkey explore closer trade ties to reduce dependence on China

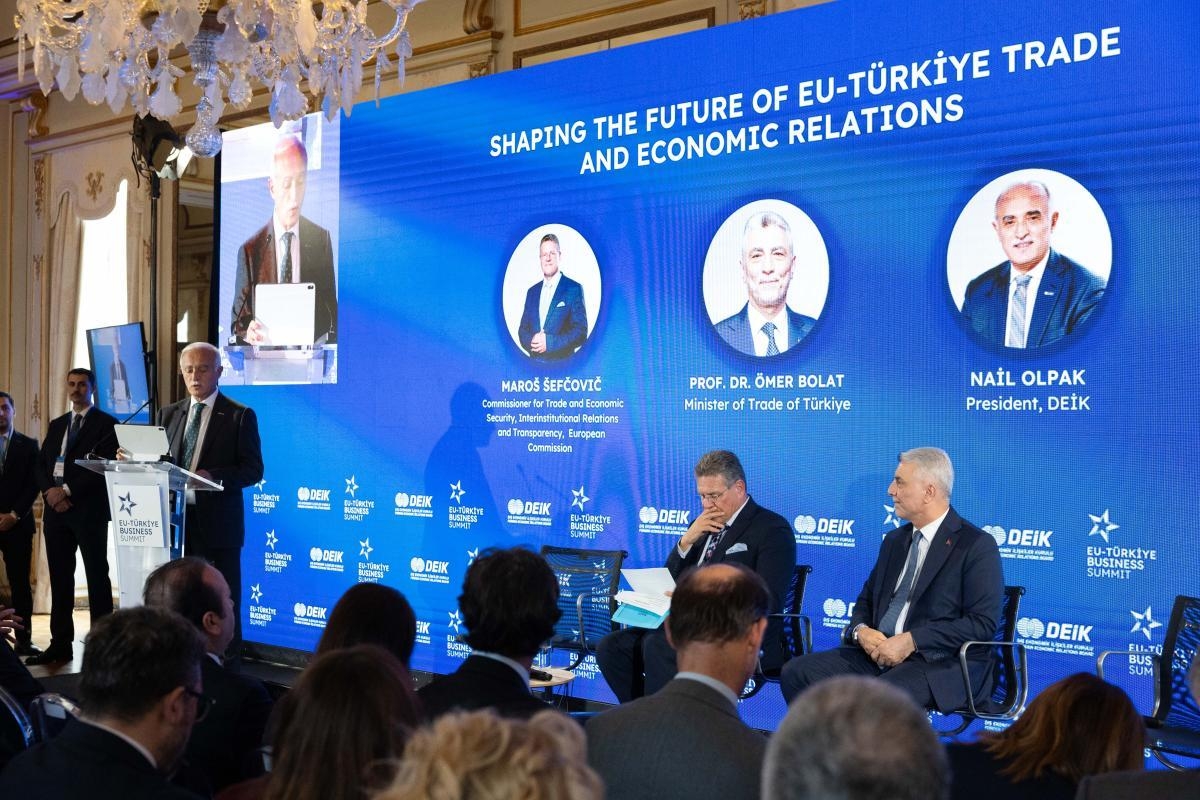
Belgium’s foreign minister has called on the EU to deepen its economic, trade, and defence ties with Turkey, amid concerns from Ankara that it risks being shut out of the bloc’s new rules on industrial supply chains and multi-billion euro defence procurement scheme. 

Speaking at a Turkey-EU business forum in Brussels on Tuesday (13 October), Belgian foreign minister Maxime Pévot said that European manufacturers were increasingly looking for reliable partners closer to home as they seek to reduce their reliance on Chinese inputs. 

“We should make values of its proximity, particularly in sectors where Europe needs to reduce strategic dependencies,” he added. 

“Our economic relationship should no longer be limited to buying and selling goods. We should also be developing, producing, and investing together,” he said. 

For his part, following talks with Ankara’s trade minister, Ömer Bolat, EU trade commissioner Maroš Šefčovič told reporters that the two sides had agreed on reforms to Turkey’s import control system to make the system easier for EU exporters to use and a mutual recognition pact on trusted traders. 

This article continues, but the full version is available only to EUobserver.com subscribers. Visit account.euobserver.com/membership

  •  

BRICS Pay, non è ancora giunto il momento?

BRICS Pay non è una valuta né una rete di regolamento: è interoperabilità. E a Nuova Delhi i leader si sono limitati a “prenderne atto”.

Segue nostro Telegram.

Cosa è e cosa non è

Alla vigilia del diciottesimo vertice BRICS, ospitato al Bharat Mandapam di Nuova Delhi il 12 e 13 settembre 2026, una parte della stampa specializzata dava per imminente il debutto di BRICS Pay. Le guide al vertice indicavano proprio la capitale indiana come sede del pieno dispiegamento del sistema, con la Reserve Bank of India incaricata del coordinamento tecnico. Il testo approvato dai leader racconta un’altra storia. La Dichiarazione di Nuova Delhi, 140 paragrafi adottati per consenso, si limita a «prendere atto» del lavoro svolto dalla BRICS Payment Task Force sull’interoperabilità dei canali di pagamento e di messaggistica e sulle discussioni relative al regolamento in valute locali, precisando che ciò avviene nel rispetto delle priorità nazionali e nella consapevolezza che non esiste una soluzione valida per tutti. La proposta indiana di collegare le valute digitali delle banche centrali, su cui Nuova Delhi aveva investito una parte consistente del capitale politico della propria presidenza, nel documento non compare.

La distanza tra attese e risultato non va letta come un incidente diplomatico. Riflette due condizioni strutturali che la pubblicistica sulla de-dollarizzazione tende a sottovalutare. La prima è che i Paesi BRICS, presi uno per uno, hanno ancora buone ragioni per regolare in dollari una parte rilevante dei propri scambi. La seconda è che un sistema di pagamento comune non è un problema di ingegneria finanziaria. È un atto di governo condiviso, che richiede regole vincolanti, un’istanza di arbitrato e la disponibilità a fidarsi delle banche centrali altrui. A Nuova Delhi nessuna di queste condizioni era sul tavolo.

Il nome induce in errore. BRICS Pay non è una moneta e non è, almeno nella configurazione discussa finora, un circuito di regolamento. È un livello di interoperabilità pensato per mettere in comunicazione sistemi nazionali già esistenti: il russo SPFS, nato dopo le sanzioni del 2014; il cinese CIPS, operativo dal 2015; l’indiano UPI e il brasiliano Pix, costruiti per i pagamenti domestici istantanei e solo in seguito proiettati all’estero. Il progetto ha preso forma durante la presidenza russa del 2024, nel quadro della BRICS Cross-Border Payments Initiative accolta a Kazan, un’iniziativa che la stessa dichiarazione di quel vertice qualificava come volontaria e non vincolante.

Per capire dove si colloca il progetto conviene distinguere tre piani che il dibattito pubblico confonde di continuo. Il primo è la messaggistica, cioè la trasmissione standardizzata degli ordini di pagamento tra istituzioni finanziarie: è il terreno di SWIFT, ed è qui che BRICS Pay si propone come alternativa. Il secondo è il regolamento, il trasferimento effettivo di valore tra conti presso banche centrali o banche corrispondenti, con tutto ciò che comporta in termini di liquidità, rischio di controparte e gestione dei saldi. Il terzo è l’unità di conto, la moneta in cui i contratti sono denominati. Un’alternativa a SWIFT agisce soltanto sul primo piano. Se un esportatore indiano fattura in dollari e la banca russa regola in dollari presso un corrispondente, aver trasmesso il messaggio su un canale non occidentale cambia ben poco.

L’interoperabilità ha però un vantaggio politico evidente, ed è la ragione per cui è diventata la formula di compromesso del gruppo: consente a ciascun Paese di conservare la propria moneta e il proprio sistema finanziario. Una moneta comune imporrebbe rinunce di tutt’altra portata, dalle regole di emissione e di cambio alla gestione dei Paesi strutturalmente in avanzo o in disavanzo. Non a caso Sudhakar Dalela, segretario per le relazioni economiche del ministero degli Esteri indiano, ha ribadito durante il vertice che una valuta BRICS non è in discussione, aggiungendo la prudente clausola «per ora».

La storia del dossier è la storia di un lessico che avanza di millimetri. Nel 2010, a Brasília, i quattro Paesi fondatori si impegnavano a studiare la fattibilità di una cooperazione monetaria e di accordi di regolamento in valuta locale. A Ufa, nel 2015, si riconosceva il potenziale delle valute nazionali; a Xiamen, due anni dopo, si parlava di swap valutari e di investimenti diretti in moneta locale. Dal 2019 l’attenzione si è spostata sulle infrastrutture di pagamento, con l’avvio dei lavori della Payment Task Force. Johannesburg, nel 2023, ha evocato per la prima volta l’interconnessione dei sistemi di pagamento transfrontalieri; Kazan ha lanciato l’iniziativa volontaria; Rio, nel 2025, ha accolto un rapporto tecnico sul sistema di pagamenti transfrontalieri BRICS che a oltre un anno di distanza non è stato reso pubblico. Sedici anni dopo Brasília, Nuova Delhi «prende atto». La successione dei verbi (studiare, riconoscere, accogliere, prendere atto) è già un indicatore: in un organismo che decide per consenso, il grado di impegno reale si legge nella grammatica dei comunicati.

L’ambizione indiana e il prezzo del consenso

L’India aveva fatto dei pagamenti transfrontalieri uno dei pilastri della propria presidenza. A gennaio la Reserve Bank of India aveva proposto di collegare le valute digitali di banca centrale dei Paesi membri per facilitare commercio e turismo; ad agosto il governatore Sanjay Malhotra confermava che erano in corso discussioni sul collegamento dei sistemi di pagamento veloce e delle CBDC; alla vigilia del vertice il ministro del Commercio Piyush Goyal rilanciava l’invito a regolare gli scambi in moneta locale. Già il 10 settembre, tuttavia, Reuters riferiva di ostacoli politici e tecnici in grado di limitare i progressi, e ne indicava due in particolare: l’interruzione dei rapporti finanziari tra Emirati Arabi Uniti e Iran e la riluttanza della stessa India ad approfondire la connettività finanziaria con la Cina senza una fiducia reciproca più solida.

Il secondo ostacolo merita attenzione, perché rovescia un’immagine corrente. Il freno più robusto a un’integrazione dei pagamenti BRICS non viene da Washington, ma dal Paese che presiedeva il vertice. Nuova Delhi vuole infrastrutture che rendano più semplice il commercio in rupie e più economiche le rimesse della sua diaspora. Non vuole che queste infrastrutture passino per nodi cinesi, né che il loro effetto netto sia un’espansione dello yuan in Asia meridionale. L’incontro tra Narendra Modi e Xi Jinping a margine del vertice ha segnato un disgelo prudente, ma il disavanzo commerciale indiano verso la Cina, raddoppiato nell’arco di un decennio, resta una frattura che nessun comunicato può ricomporre.

C’è poi l’effetto dell’allargamento. Con undici membri e dieci Paesi partner, il gruppo comprende oggi Stati che nella guerra del 2026 si sono trovati su fronti opposti. A maggio la riunione dei ministri degli Esteri, sempre a Nuova Delhi, si era chiusa senza un comunicato congiunto, costringendo la presidenza indiana a una dichiarazione a titolo proprio. L’unanimità di settembre è stata ottenuta abbassando la soglia degli impegni. La dichiarazione critica dazi e sanzioni unilaterali senza nominare gli Stati Uniti e, sul dossier finanziario, rinvia a un lavoro tecnico di cui non fissa né scadenze né obiettivi. Ajay Srivastava, fondatore del Global Trade Research Initiative, ha osservato che il testo non prevede alcuna azione concreta e che, in assenza di un piano coordinato, il commercio in valute locali potrà crescere solo gradualmente, senza raggiungere volumi significativi.

Va segnalato, per scrupolo di metodo, che alcune testate hanno presentato il vertice come il momento del «lancio» di BRICS Pay. Il testo della dichiarazione, così come riportato dalle fonti che lo hanno esaminato nel dettaglio, non autorizza questa lettura. La confusione tra annuncio e realizzazione è uno dei tratti ricorrenti della comunicazione sul tema, e contribuisce a gonfiare aspettative che poi ricadono sulla credibilità del gruppo.

Le buone ragioni del dollaro

Le statistiche disponibili spiegano meglio di qualsiasi dichiarazione perché la de-dollarizzazione resti, per ora, più un tema di dibattito che una tendenza misurabile. Secondo l’ultima indagine triennale della Banca dei regolamenti internazionali, nell’aprile 2025 il dollaro compariva in circa l’89% delle transazioni valutarie mondiali, una quota in lieve aumento rispetto al 2022, mentre lo yuan si fermava all’8,5%. Sul versante delle riserve, i dati del Fondo monetario internazionale indicano per il primo trimestre del 2026 una quota del dollaro pari al 57,13%, contro l’1,99% della valuta cinese. La tendenza di lungo periodo è di erosione: intorno al 1999 il dollaro superava il 70% delle riserve allocate. Ma la diversificazione si disperde su una costellazione di valute minori, la cui quota residua è più che raddoppiata dal 2021, e non si concentra sulle monete dei Paesi BRICS.

La ragione non è la sudditanza, è il calcolo. Il dollaro offre ciò che nessuna alternativa offre ancora: mercati profondi e liquidi, strumenti di copertura a basso costo, un enorme stock di debito denominato nella stessa valuta e la possibilità di convertire in qualsiasi momento il ricavato di una transazione in un attivo considerato sicuro. Barry Eichengreen ha descritto questi vantaggi in termini di effetti di rete: una moneta è utile in proporzione al numero di soggetti che già la usano, e ciò rende costosa qualunque transizione tentata da un solo attore o da un piccolo gruppo. Per un importatore brasiliano o un esportatore indonesiano pagare in dollari significa pagare nella moneta che la controparte accetta senza trattare.

Scendendo al livello dei singoli membri, il quadro si fa ancora più netto. L’India ha dichiarato a più riprese di non avere interesse a indebolire il dollaro: nel dicembre 2024 il ministro degli Esteri Subrahmanyam Jaishankar ricordava che gli Stati Uniti sono il primo partner commerciale del Paese, e nell’estate 2025 il portavoce del ministero ribadiva che la de-dollarizzazione non rientra nell’agenda finanziaria indiana. Emirati Arabi Uniti e Arabia Saudita mantengono le proprie valute ancorate al dollaro e fondano la propria sicurezza su un rapporto con Washington che nessun circuito di pagamento alternativo potrebbe compensare. Riyadh, del resto, continua a stare nel gruppo in una posizione ambigua: la presidenza indiana la elencava tra gli undici membri, ma a Nuova Delhi la delegazione saudita si è presentata con lo status di Paese invitato. Egitto ed Etiopia, che negli ultimi anni hanno negoziato programmi con il Fondo monetario e portano un debito estero in valuta forte, non possono permettersi di complicare il rapporto con i propri creditori. Il Brasile di Lula ha rilanciato più volte l’idea di una moneta commerciale comune, ma il suo sistema di punta, Pix, rimane un successo domestico.

Restano la Russia e l’Iran, per i quali l’uscita dal dollaro non è una scelta ma una necessità imposta dalle sanzioni, e la Cina, che ha un interesse reale all’internazionalizzazione dello yuan ma lo persegue attraverso infrastrutture proprie, a cominciare da CIPS, e senza rinunciare ai controlli sui capitali che limitano l’attrattiva della sua moneta come riserva. Anche per chi ha le motivazioni più forti, tuttavia, il regolamento in valute locali ha mostrato limiti precisi. L’esperienza russo-indiana è istruttiva. Il forte aumento delle importazioni indiane di petrolio russo dopo il 2022 ha lasciato Mosca con ingenti saldi in rupie difficili da impiegare, un problema che lo stesso Sergej Lavrov ammise pubblicamente nel maggio 2023. Quando gli scambi sono squilibrati, la moneta del Paese in disavanzo si accumula presso il Paese in avanzo, e il dollaro torna a essere la via d’uscita più semplice.

A questi incentivi si somma il costo esplicito di una rottura. Donald Trump ha minacciato dazi del 100% contro i Paesi BRICS che sostenessero una moneta alternativa al dollaro e, dopo il vertice di Rio del 2025, un dazio aggiuntivo del 10% per chi si allineasse alle politiche del gruppo da lui definite antiamericane. Alla vigilia di Nuova Delhi l’economista di Natixis Alicia García-Herrero prevedeva che i leader avrebbero discusso di pagamenti transfrontalieri senza tentare di sostituire il dollaro. È andata esattamente così.

Una scelta politica

Si arriva così al punto centrale. Un sistema di pagamento non è un’infrastruttura neutrale. Susan Strange collocava la struttura finanziaria, cioè il controllo sul credito e sui canali attraverso cui circola, tra le quattro fonti del potere strutturale nell’economia politica internazionale. Gli Stati che controllano i nodi centrali delle reti economiche globali, di cui SWIFT è l’esempio canonico, possano trasformarli in strumenti di coercizione, sfruttandone sia la funzione di osservatorio sia la capacità di esclusione. È proprio questa esperienza, culminata nell’esclusione delle principali banche russe da SWIFT nel 2022, ad aver dato slancio politico al progetto BRICS.

La stessa lezione, però, vale all’interno del gruppo. Chi costruisce una rete alternativa deve stabilire dove si trovano i nodi, chi ne gestisce i dati, quale diritto regola le controversie, chi fornisce liquidità nei momenti di tensione e come si compensano i saldi tra economie in avanzo e in disavanzo. Ognuna di queste decisioni redistribuisce potere. Per l’India un sistema imperniato su CIPS significherebbe sostituire una dipendenza da Washington con una dipendenza da Pechino, cioè da un rivale con cui condivide una frontiera contesa. Per gli Emirati collegarsi a un circuito in cui transita l’Iran vorrebbe dire esporsi al rischio di sanzioni secondarie, proprio mentre i due Paesi escono da una guerra vissuta su fronti opposti. Il problema non è la tecnologia: le componenti nazionali esistono e funzionano. Manca un accordo su chi governa l’insieme.

La storia monetaria del Novecento offre due riferimenti utili. Il primo è la proposta keynesiana di una International Clearing Union, presentata dal Tesoro britannico nel 1943, che affrontava esattamente il nodo degli squilibri persistenti imponendo oneri simmetrici ai Paesi in avanzo e a quelli in disavanzo. Un BRICS Pay che volesse andare oltre la messaggistica avrebbe bisogno di un meccanismo analogo di compensazione multilaterale, e dunque di regole capaci di vincolare anche la Cina, principale creditore commerciale del gruppo. Il secondo riferimento è la tesi di Charles Kindleberger sulla stabilità del sistema internazionale come bene pubblico, che richiede un attore disposto a sostenerne i costi. Nell’ordine del dollaro quel ruolo è svolto, con tutti gli abusi che ne derivano, dagli Stati Uniti. Nel partenariato BRICS l’unico candidato plausibile è la Cina, e gli altri membri non intendono riconoscerle quella funzione. Qui sta il dilemma costitutivo di un ordine monetario multipolare: moltiplica i poli, ma lascia vacante il posto di chi garantisce il sistema.

A ciò si aggiunge la fragilità istituzionale. Il gruppo opera senza un segretariato permanente, con presidenze annuali a rotazione che affidano la continuità dei dossier tecnici alla volontà del Paese di turno. L’allargamento ha accresciuto l’eterogeneità degli interessi senza dotare il partenariato di strumenti decisionali più robusti. Un sistema di pagamento unificato richiederebbe un trattato, o almeno un accordo vincolante di governance, mentre l’iniziativa sui pagamenti transfrontalieri è, per esplicita scelta dei firmatari, volontaria e non vincolante. Finché questa asimmetria tra ambizione e forma giuridica non sarà sciolta, BRICS Pay resterà ciò che è oggi: un marchio politico sovrapposto a un insieme di corridoi bilaterali. La stabilità del partenariato non è dunque una condizione accessoria del progetto. Ne è il presupposto.

Verso la presidenza cinese del 2027

Con il passaggio della presidenza alla Cina per il 2027, l’orizzonte di valutazione più utile è quello dei prossimi diciotto-ventiquattro mesi. Le valutazioni che seguono poggiano su evidenze di qualità moderata, costituite in larga parte dai testi ufficiali e dalla stampa economica internazionale.

Lo scenario che considero altamente probabile è quello di un mosaico bilaterale. Crescono i corridoi già avviati, come quelli tra India ed Emirati e tra India e Russia, mentre l’architettura comune resta allo stadio di studio. Il commercio in valute locali aumenta in termini assoluti, ma la quota del dollaro negli scambi intra-BRICS si riduce solo in misura marginale.

Uno scenario alternativo, cui attribuisco una probabilità moderata, prevede che la presidenza cinese usi il 2027 per promuovere un nucleo a geometria variabile, costruito attorno a CIPS e SPFS, con l’adesione di Russia, Iran e di alcuni Paesi partner. Il marchio BRICS Pay verrebbe formalmente attivato, ma per una parte soltanto del gruppo e con ogni probabilità senza l’India. Sarebbe un risultato politicamente spendibile per Pechino e Mosca, ma renderebbe esplicita la frattura che oggi il linguaggio delle dichiarazioni riesce ancora a coprire.

L’entrata in funzione, entro il 2028, di un sistema unificato e operativo per tutti i membri resta invece altamente improbabile.

Gli indicatori da seguire sono pochi e concreti: la pubblicazione del rapporto tecnico accolto a Rio; l’eventuale firma di un accordo vincolante sulla governance dei pagamenti; la creazione di un meccanismo multilaterale di compensazione o di linee di swap dedicate, magari affidate alla Nuova Banca di Sviluppo; la posizione indiana su un collegamento con CIPS; la formalizzazione, o il definitivo abbandono, della membership saudita. Un comunicato che parli di «lancio» senza alcuno di questi elementi andrà letto per ciò che è, un annuncio.

Il multipolarismo ha finora prodotto soprattutto una pluralità di opzioni nazionali, utili a ciascun Paese per ridurre l’esposizione alle sanzioni e per negoziare da posizioni migliori con Washington. Trasformare queste opzioni in un sistema richiede un partenariato che riconosca un interesse comune più forte delle rivalità interne. Quel partenariato è ancora in evoluzione, e BRICS Pay ne seguirà i tempi, non il contrario.

  •  

EU Caps Chinese Hybrid Car Imports at 350,000 as Brussels Moves to Protect Europe’s Motor Industry

The European Union has reached an agreement with China to restrict imports of Chinese hybrid vehicles to 350,000 annually, introducing a significant new barrier to the expansion of Chinese manufacturers in Europe’s automotive market.

The arrangement, confirmed on 12 October, follows months of negotiations between Brussels and Beijing and reflects growing concern about the competitive position of European carmakers.

The import ceiling could reduce Chinese hybrid vehicle sales in the EU by more than half compared with previously anticipated volumes, although the actual effect will depend on demand, product classifications and implementation.

The agreement comes as manufacturers gather for the Paris Motor Show, where the future of European vehicle production, Chinese competition and industrial policy have become central subjects.

China’s Commerce Ministry has presented the outcome as a negotiated arrangement intended to preserve trading relations, while the European side has emphasised the need to prevent rapidly increasing imports from undermining domestic production.

Chinese manufacturers confront a new European barrier

Chinese carmakers have expanded aggressively in overseas markets as domestic demand has weakened. Chinese passenger vehicle exports rose sharply in September, with manufacturers increasingly targeting Europe, Latin America and Asian markets.

Hybrid vehicles have become particularly important because they offer consumers lower fuel consumption without requiring the same degree of dependence on charging infrastructure as fully electric cars.

This has allowed Chinese brands to compete in market segments where European manufacturers retain substantial established production capacity.

The new quota limits the number of eligible Chinese hybrid vehicles permitted to enter the European market each year. According to details of the import restrictions, shipments exceeding the permitted volume would face restrictions at EU customs.

The mechanism differs from a conventional tariff because imports beyond the ceiling cannot simply enter the market by paying a higher duty. Manufacturers and importers will need to consider both delivery costs and the availability of import allocations.

European manufacturers seek protection

The measures arrive amid growing pressure on the European automotive industry, which faces high production costs, expensive energy, competition from Chinese manufacturers and the capital requirements of shifting towards electrified transport.

Companies operating in Germany, France, Italy and other established manufacturing centres must fund the development of new vehicles while maintaining existing factories and employment.

Chinese manufacturers benefit from extensive domestic production networks, considerable scale and access to battery manufacturing capacity.

European policymakers have questioned whether competition takes place under equivalent economic conditions, particularly where Chinese producers receive support from state-directed industrial policies.

Beijing rejects allegations that its export performance results principally from unfair state assistance, arguing that Chinese companies have achieved competitiveness through investment, innovation and efficiency.

The quota represents a departure from the assumption that European consumers will necessarily have unrestricted access to the lowest-priced imported vehicles.

Its economic effects will depend partly on whether European manufacturers can use the additional protection to improve productivity and develop more competitive models.

Will Chinese manufacturers move production into Europe?

Restrictions on imports do not necessarily reduce the presence of Chinese-owned companies in the European automotive industry.

Several manufacturers are already developing production capacity outside China, including within the European Union. BYD’s investment in Hungary is one example of how Chinese companies can pursue access to European consumers through local manufacturing rather than relying entirely on imported finished vehicles.

The new arrangements could strengthen the commercial incentive to expand such operations.

For European governments, Chinese investment presents a difficult calculation. New factories may create employment, increase industrial activity and preserve automotive supply chains, while also expanding the influence of Chinese manufacturers within Europe’s domestic market.

The economic consequences depend on how much research, component manufacturing, battery production and other high-value activity takes place locally.

A Chinese-owned assembly plant using predominantly imported components would provide different benefits from a fully developed European production network.

The British dimension

The debate is also drawing attention to the position of the United Kingdom, whose automotive industry remains closely integrated with European supply chains despite Brexit.

Executives from Stellantis and Renault have supported including Britain within proposed European industrial protection measures, reflecting the importance of UK manufacturing operations to their broader businesses.

Such an arrangement would raise questions about regulatory alignment, trade preferences and the conditions under which non-EU production could qualify for European industrial support.

British manufacturers also face the challenge of Chinese competition, and decisions taken in Brussels could influence investment strategies across the wider European automotive sector.

Protection versus competitiveness

The restrictions may offer European manufacturers additional time to adapt, but they do not eliminate the structural challenges confronting the industry.

Energy prices, labour costs, the availability of batteries and the affordability of new vehicles remain important factors in the competitiveness of European production.

Nor will the quota necessarily prevent Chinese firms from gaining market share through investment, partnerships or vehicles manufactured outside China.

The EU’s approach combines restrictions on imports with the possibility of continued Chinese industrial participation inside Europe.

The outcome will depend on whether European manufacturers use the reduced competitive pressure to strengthen their technological and manufacturing position, or whether the restrictions primarily accelerate the relocation of Chinese-owned production into the EU.

  •  

EU trade chief hails ‘crucial first step’ as Beijing talks avoid trade war

EU and Chinese officials agreed a series of trade concessions covering electric cars, rare earths and tariffs that dragged them away from a damaging trade war on Friday (9 October), following two days of crisis talks.

Following two days of talks in Beijing, EU trade commissioner Maroš Šefčovič said that he and China’s commerce secretary Wang Wentao had made a “crucial first step” towards rebalancing EU-China trade relations.

Europe can point to progress on hybrid vehicles, stronger assurances over the supply of critical raw materials, and continued engagement on market access issues in China.

Hours before Šefčovič arrived, Beijing rejected an EU demand for so-called “voluntary export restrictions” on its electric vehicles (EVs). However, in a joint statement on Friday, the two sides said that they had reached an “understanding on trade in hybrid vehicles in a WTO compliant manner”, but without providing further details.

They added that further negotiations on reducing tariffs and minimum pricing deals would allow Chinese EVs to enter the EU at a lower duty rate.

This article continues, but the full version is available only to EUobserver.com subscribers. Visit account.euobserver.com/membership

  •  
❌